Judicial review of settlement orders cannot reopen settled customs notices, while statutory interest remains subject to verification and quantificatio...
Customs Broker licence lending for consideration justified revocation where exporter authorisation and client verification obligations were also breac...
Fraudulent import documents suspend limitation protection, while redemption of confiscated goods requires duty and interest despite bona fide purchase...
ODR arbitration participation remains mandatory after failed conciliation, while jurisdictional and maintainability objections stay available before t...
Transparency in technical bid evaluation requires disclosed standards and recorded reasons; opaque scoring invalidated tender awards and required fres...
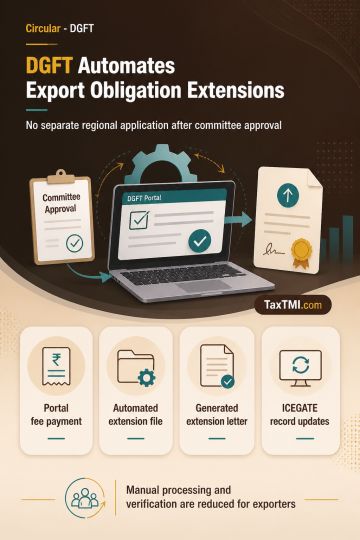
Automated export obligation extensions remove separate regional applications after committee approval for Advance Authorisation and EPCG authorisation...
Where an income-tax refund is due and adjustment against an outstanding demand is proposed under section 245 of the Income-tax Act, 1961, the tax department may retain only the amount proposed for adjustment or withholding. It must promptly release the balance refund, without prejudicing either party's right to challenge the legality of the outstanding demand or the proposed adjustment. The balance refund was directed to be credited within the stipulated period; failure to do so would attract interest at the rate directed by the High Court.
Where an income-tax refund is due and adjustment against an outstanding demand is proposed under section 245 of the Income-tax Act, 1961, the tax department may retain only the amount proposed for adjustment or withholding. It must promptly release the balance refund, without prejudicing either party's right to challenge the legality of the outstanding demand or the proposed adjustment. The balance refund was directed to be credited within the stipulated period; failure to do so would attract interest at the rate directed by the High Court.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888