Penny-stock additions require transaction-specific evidence; general investigation material alone cannot establish undisclosed income or accommodation...
Transfer pricing comparability prioritises reliable external CUPs and foreign-currency LIBOR benchmarks for exports, borrowings and delayed receivable...
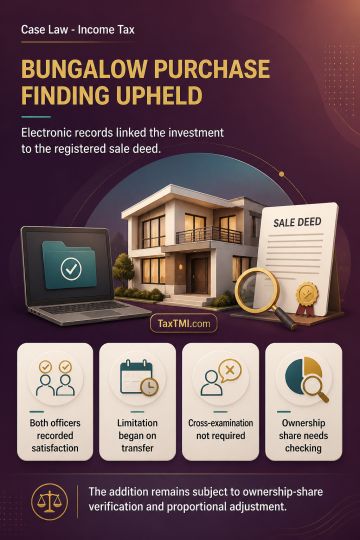
Section 153C satisfaction and seized electronic records sustained unexplained-investment addition, subject to proportionate ownership-share verificati...
Natural justice in insolvency-professional discipline requires disclosed material; notices based on extraneous material and ignored defences are vitia...
Page of 4939
Press 'Enter' after typing page number.
2541 to 2560 of 98775 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Section 153C jurisdiction was upheld by the majority because...
Section 153C satisfaction and seized electronic records sustained unexplained-investment addition, subject to proportionate ownership-share verification.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Section 153C jurisdiction was upheld by the majority because both Assessing Officers recorded satisfaction that seized material related to the assessee and affected income determination. No prescribed period governed satisfaction by the Assessing Officer of the other person, and assessment limitation ran from transfer of the seized material. Natural justice did not require supplying statements or permitting cross-examination because the addition rested on seized electronic records rather than witness statements. The seized Excel sheet was treated as corroborated evidence of unexplained investment in a jointly acquired bungalow, as its transaction particulars matched the registered sale deed. The addition remained sustained, subject to verification of the assessee's ownership share and proportionate adjustment.
Section 153C jurisdiction was upheld by the majority because both Assessing Officers recorded satisfaction that seized material related to the assessee and affected income determination. No prescribed period governed satisfaction by the Assessing Officer of the other person, and assessment limitation ran from transfer of the seized material. Natural justice did not require supplying statements or permitting cross-examination because the addition rested on seized electronic records rather than witness statements. The seized Excel sheet was treated as corroborated evidence of unexplained investment in a jointly acquired bungalow, as its transaction particulars matched the registered sale deed. The addition remained sustained, subject to verification of the assessee's ownership share and proportionate adjustment.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4939