Urgent interim relief exception permits commercial suit without pre-institution mediation where immediate disclosure and asset protection are genuinel...
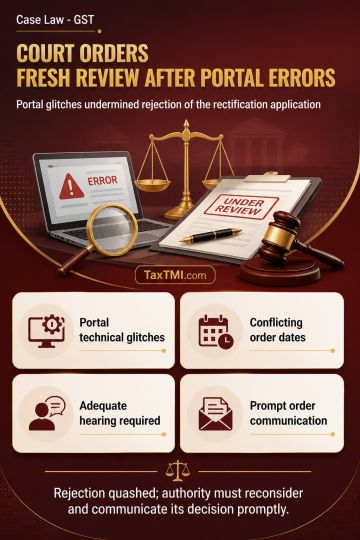
Portal order discrepancies invalidated rectification rejection, requiring fresh reasoned consideration after hearing and prompt communication of the o...
Recurring trademark fees paid under a non-exclusive, time-bound licence are revenue expenditure where proprietary rights remain with the licensor. The enduring benefit test requires examination of whether the agreement transfers ownership, exclusive rights, or a lasting capital asset. Limited permission to use a trademark, coupled with an obligation to stop using it on termination, does not create such an asset. Annual fees calculated as a percentage of gross profit are recurring operational payments and remain deductible as revenue expenditure. The disallowance of the licensed trademark fee was therefore deleted.
Recurring trademark fees paid under a non-exclusive, time-bound licence are revenue expenditure where proprietary rights remain with the licensor. The enduring benefit test requires examination of whether the agreement transfers ownership, exclusive rights, or a lasting capital asset. Limited permission to use a trademark, coupled with an obligation to stop using it on termination, does not create such an asset. Annual fees calculated as a percentage of gross profit are recurring operational payments and remain deductible as revenue expenditure. The disallowance of the licensed trademark fee was therefore deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894