Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
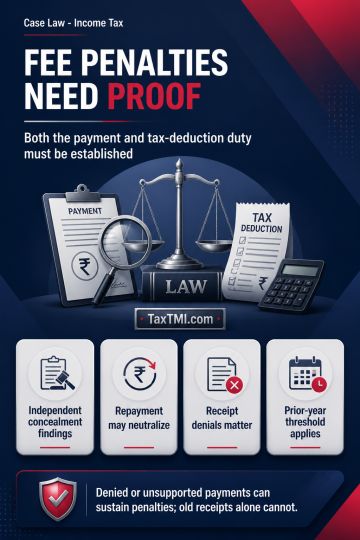
Penalty for inaccurate particulars in professional-fee claims requires substantiated expenditure and independent findings supporting concealment or inaccurate particulars. A payment characterised as professional fees but shown to be a loan advanced and repaid, with a corresponding receipt credited to profit and loss, is revenue neutral and does not support disallowance or penalty. Conversely, penalty remains justified where claimed payees deny receipt or payments remain unsubstantiated. Liability to deduct tax on professional fees depends on satisfying the statutory threshold based on gross receipts in the immediately preceding financial year; older receipt data alone is insufficient. Disallowance for non-deduction of tax does not, by itself, justify penalty.
Penalty for inaccurate particulars in professional-fee claims requires substantiated expenditure and independent findings supporting concealment or inaccurate particulars. A payment characterised as professional fees but shown to be a loan advanced and repaid, with a corresponding receipt credited to profit and loss, is revenue neutral and does not support disallowance or penalty. Conversely, penalty remains justified where claimed payees deny receipt or payments remain unsubstantiated. Liability to deduct tax on professional fees depends on satisfying the statutory threshold based on gross receipts in the immediately preceding financial year; older receipt data alone is insufficient. Disallowance for non-deduction of tax does not, by itself, justify penalty.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916