Agricultural land classification requires cumulative factual indicators, while industrial-purpose land and absent agricultural use defeat reinvestment...
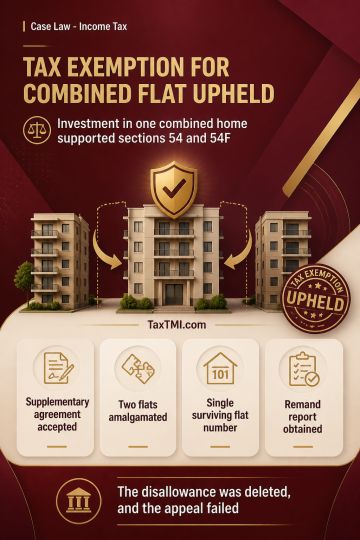
Composite residential flat exemption upheld where supplementary agreement merged adjoining units and additional evidence supported the taxpayer's inve...
Urgent interim relief exception permits commercial suit without pre-institution mediation where immediate disclosure and asset protection are genuinel...
Residuary penalty under section 117 of the Customs Act was unsustainable where specific penal provisions were available and the importer's omission arose from the supplier's failure to provide an invoice. After clearance, the importer verified the consignment, voluntarily disclosed the omitted invoice to Customs, and sought reassessment to pay duty on the entire consignment. As no material showed that Customs would otherwise have detected the irregularity, the Tribunal set aside the penalty imposed under section 117, allowed the appeal, and granted consequential relief.
Residuary penalty under section 117 of the Customs Act was unsustainable where specific penal provisions were available and the importer's omission arose from the supplier's failure to provide an invoice. After clearance, the importer verified the consignment, voluntarily disclosed the omitted invoice to Customs, and sought reassessment to pay duty on the entire consignment. As no material showed that Customs would otherwise have detected the irregularity, the Tribunal set aside the penalty imposed under section 117, allowed the appeal, and granted consequential relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891