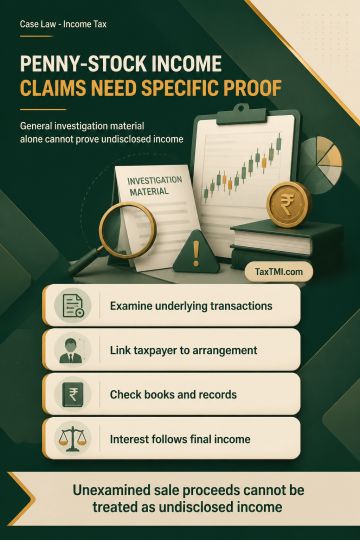
Penny-stock additions require transaction-specific evidence; general investigation material alone cannot establish undisclosed income or accommodation...
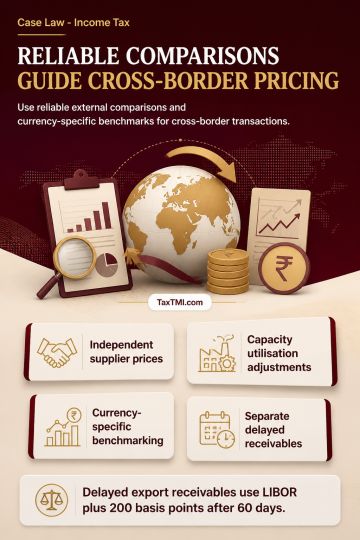
Transfer pricing comparability prioritises reliable external CUPs and foreign-currency LIBOR benchmarks for exports, borrowings and delayed receivable...
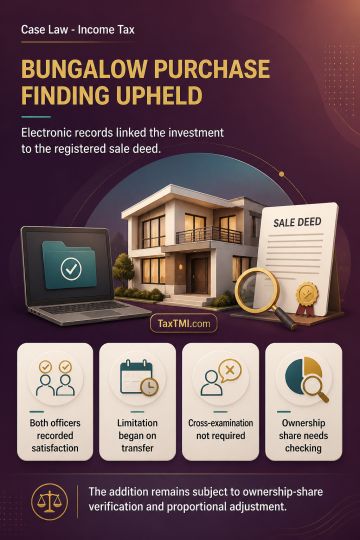
Section 153C satisfaction and seized electronic records sustained unexplained-investment addition, subject to proportionate ownership-share verificati...
Natural justice in insolvency-professional discipline requires disclosed material; notices based on extraneous material and ignored defences are vitia...
Page of 4935
Press 'Enter' after typing page number.
2461 to 2480 of 98695 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Under Section 138B, a customs statement offered to prove its contents is relevant only in prescribed circumstances. A retracted statement, where specifically requested cross-examination is refused, cannot serve as legal evidence against a noticee. In confiscation proceedings, untested statements cannot independently establish that seized gold was smuggled or that the person knew it was liable to confiscation. Denial of cross-examination undermines confiscation and penalty findings under customs law.
Under Section 138B, a customs statement offered to prove its contents is relevant only in prescribed circumstances. A retracted statement, where specifically requested cross-examination is refused, cannot serve as legal evidence against a noticee. In confiscation proceedings, untested statements cannot independently establish that seized gold was smuggled or that the person knew it was liable to confiscation. Denial of cross-examination undermines confiscation and penalty findings under customs law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935