Customs assessment information portal centralises rulings and guidance to promote consistent classification, valuation, transparency and informed comp...
Composite show-cause notices spanning multiple financial years are jurisdictionally invalid, allowing writ review despite an alternative appellate rem...
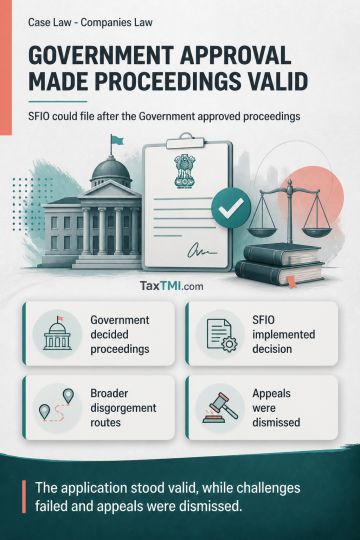
Authorization to the SFIO Director to present attachment and disgorgement proceedings in the Union of India's name does not constitute delegation of statutory power where the Central Government has already considered the investigation report, decided to institute proceedings, and retains essential decision-making discretion. The application was therefore validly instituted through an authorised officer. Disgorgement and asset-freezing relief for oppression, mismanagement and fraudulent conduct are not confined to Section 212(14A); they may also be pursued under the statutory framework governing such conduct. The challenge to SFIO's authority and the claim that Section 212(14A) was the exclusive source of disgorgement power were rejected, and the appeals were dismissed.
Authorization to the SFIO Director to present attachment and disgorgement proceedings in the Union of India's name does not constitute delegation of statutory power where the Central Government has already considered the investigation report, decided to institute proceedings, and retains essential decision-making discretion. The application was therefore validly instituted through an authorised officer. Disgorgement and asset-freezing relief for oppression, mismanagement and fraudulent conduct are not confined to Section 212(14A); they may also be pursued under the statutory framework governing such conduct. The challenge to SFIO's authority and the claim that Section 212(14A) was the exclusive source of disgorgement power were rejected, and the appeals were dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937