Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Page of 4935
Press 'Enter' after typing page number.
2081 to 2100 of 98695 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Long-term leases conferring development rights, possession and...
Development rights transfers treated as immovable property, while construction abatement applies and repeated non-payment permits extended service-tax limitation.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
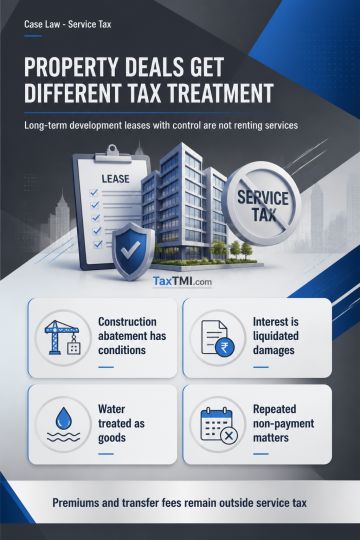
Long-term leases conferring development rights, possession and effective control for a one-time premium are treated as transfers of immovable property rather than taxable renting services; associated premiums and transfer fees are consequently outside service tax. Construction of residential complexes remains taxable, but prescribed abatement applies where its conditions are met and CENVAT credit has been reversed. Interest charged for delayed payment of unit-sale consideration is liquidated damages, not service consideration. Water supplied by a governmental development authority in a sovereign function is treated as goods supply rather than taxable service. Repeated non-payment after prior notice and confirmation supports extended limitation for the residual liability.
Long-term leases conferring development rights, possession and effective control for a one-time premium are treated as transfers of immovable property rather than taxable renting services; associated premiums and transfer fees are consequently outside service tax. Construction of residential complexes remains taxable, but prescribed abatement applies where its conditions are met and CENVAT credit has been reversed. Interest charged for delayed payment of unit-sale consideration is liquidated damages, not service consideration. Water supplied by a governmental development authority in a sovereign function is treated as goods supply rather than taxable service. Repeated non-payment after prior notice and confirmation supports extended limitation for the residual liability.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935