Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Special insurance income computation preserves statutory deductions while limiting transfer-pricing, withholding and disallowance adjustments for gene...
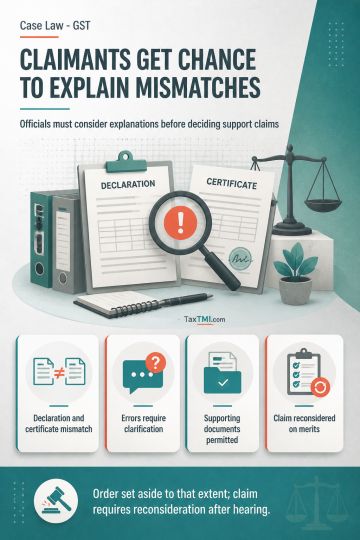
Fair hearing in budgetary support claims requires the claimant to receive an opportunity to explain discrepancies between an input tax credit declaration and a Chartered Accountant certificate submitted at the respondents' direction. Where the declaration contains an asserted error, the officer must call for an explanation and consider supporting material before concluding the claim on merits. A claim cannot be finally determined merely by relying on the discrepant declaration without this opportunity. The challenged order was set aside to that extent, with directions to permit supporting documents and reconsider the claim after a reasonable hearing.
Fair hearing in budgetary support claims requires the claimant to receive an opportunity to explain discrepancies between an input tax credit declaration and a Chartered Accountant certificate submitted at the respondents' direction. Where the declaration contains an asserted error, the officer must call for an explanation and consider supporting material before concluding the claim on merits. A claim cannot be finally determined merely by relying on the discrepant declaration without this opportunity. The challenged order was set aside to that extent, with directions to permit supporting documents and reconsider the claim after a reasonable hearing.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897