GST payment representations require record-based, reasoned decisions while substantive entitlement remains open for determination by competent authori...
Reassessment sanction under extended limitation required approval from the competent specified authority, invalidating proceedings approved by an inco...
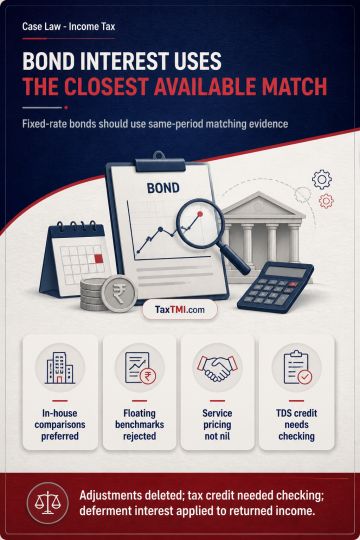
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Page of 4937
Press 'Enter' after typing page number.
2101 to 2120 of 98738 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
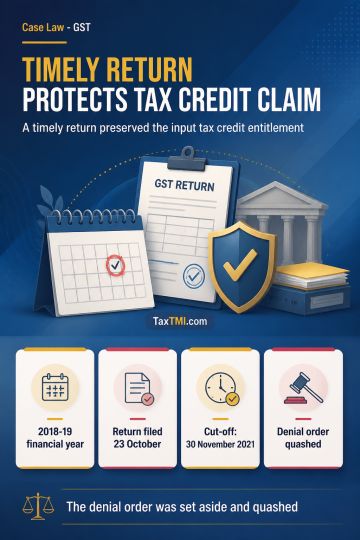
Section 16(5) of the Central Goods and Services Tax Act overrides section 16(4) and preserves input tax credit entitlement for specified financial years where the return under section 39 was filed by 30 November 2021. For Financial Year 2018-19, a return filed on 23 October 2019 fell within the preserved period. Denial of the related input tax credit was therefore impermissible, and the Order-in-Original denying the claim was set aside and quashed.
Note: It is a system-generated summary and is for quick reference only.