Natural justice in insolvency-professional discipline requires disclosed material; notices based on extraneous material and ignored defences are vitia...
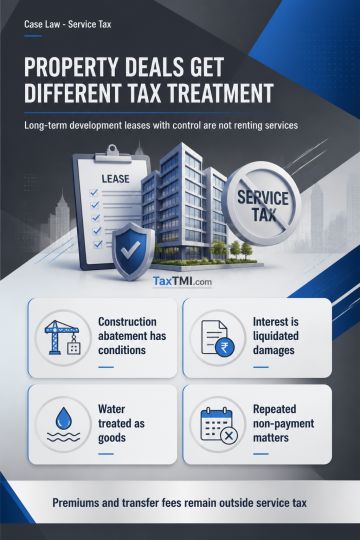
Development rights transfers treated as immovable property, while construction abatement applies and repeated non-payment permits extended service-tax...
Page of 4888
Press 'Enter' after typing page number.
1521 to 1540 of 97750 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
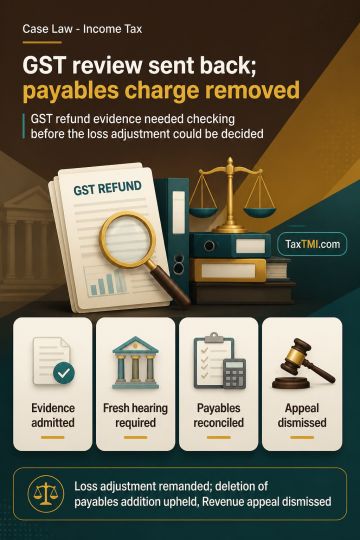
Additional documentary evidence on the GST refund mismatch was admitted as vital to verifying its accounting and tax treatment. Because the evidence required verification by the Assessing Officer and the Revenue did not oppose admission, the adjustment reducing the returned business loss was set aside and remanded for fresh adjudication after a hearing. Outstanding trade payables arising from purchases could not be treated as unexplained cash credit where creditor-balance differences had been reconciled and supported by documentary evidence. In the absence of contrary material or precedent from the Revenue, deletion of that addition was upheld and the Revenue's appeal was dismissed.
Additional documentary evidence on the GST refund mismatch was admitted as vital to verifying its accounting and tax treatment. Because the evidence required verification by the Assessing Officer and the Revenue did not oppose admission, the adjustment reducing the returned business loss was set aside and remanded for fresh adjudication after a hearing. Outstanding trade payables arising from purchases could not be treated as unexplained cash credit where creditor-balance differences had been reconciled and supported by documentary evidence. In the absence of contrary material or precedent from the Revenue, deletion of that addition was upheld and the Revenue's appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888