Service of notice and contractual debt acknowledgment preserved insolvency admission against a corporate guarantor despite limitation and natural just...
Original works exemption excludes standalone boulder transportation, leaving subcontracted railway-project transport services subject to service tax l...
Annual production capacity determinations excluding stenter galleries support refunds for unconstitutional excise levies without an unjust-enrichment ...
Vicarious liability for cheque dishonour requires specific allegations of responsibility and cheque signatory; generic director allegations cannot sus...
IT Resilience Index requires market infrastructure institutions to automate resilience scoring, early warnings, and continuous service-delivery monito...
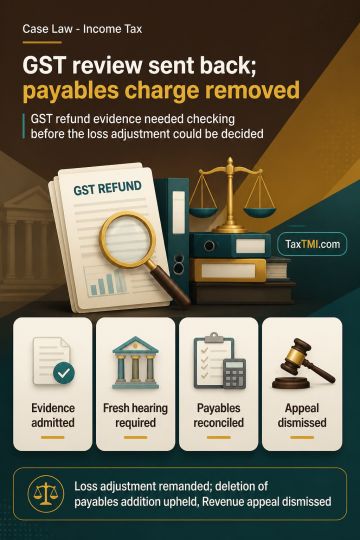
Additional documentary evidence on the GST refund mismatch was admitted as vital to verifying its accounting and tax treatment. Because the evidence required verification by the Assessing Officer and the Revenue did not oppose admission, the adjustment reducing the returned business loss was set aside and remanded for fresh adjudication after a hearing. Outstanding trade payables arising from purchases could not be treated as unexplained cash credit where creditor-balance differences had been reconciled and supported by documentary evidence. In the absence of contrary material or precedent from the Revenue, deletion of that addition was upheld and the Revenue's appeal was dismissed.
Additional documentary evidence on the GST refund mismatch was admitted as vital to verifying its accounting and tax treatment. Because the evidence required verification by the Assessing Officer and the Revenue did not oppose admission, the adjustment reducing the returned business loss was set aside and remanded for fresh adjudication after a hearing. Outstanding trade payables arising from purchases could not be treated as unexplained cash credit where creditor-balance differences had been reconciled and supported by documentary evidence. In the absence of contrary material or precedent from the Revenue, deletion of that addition was upheld and the Revenue's appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888