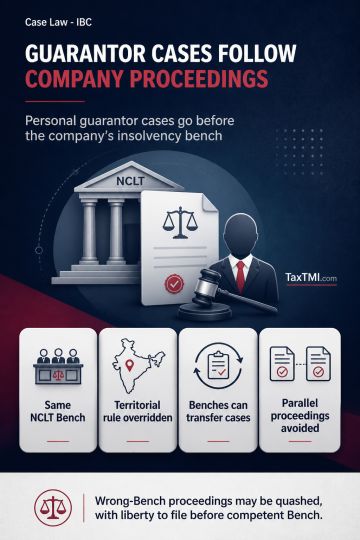
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
Additional documentary evidence on the GST refund mismatch was admitted as vital to verifying its accounting and tax treatment. Because the evidence required verification by the Assessing Officer and the Revenue did not oppose admission, the adjustment reducing the returned business loss was set aside and remanded for fresh adjudication after a hearing. Outstanding trade payables arising from purchases could not be treated as unexplained cash credit where creditor-balance differences had been reconciled and supported by documentary evidence. In the absence of contrary material or precedent from the Revenue, deletion of that addition was upheld and the Revenue's appeal was dismissed.
Additional documentary evidence on the GST refund mismatch was admitted as vital to verifying its accounting and tax treatment. Because the evidence required verification by the Assessing Officer and the Revenue did not oppose admission, the adjustment reducing the returned business loss was set aside and remanded for fresh adjudication after a hearing. Outstanding trade payables arising from purchases could not be treated as unexplained cash credit where creditor-balance differences had been reconciled and supported by documentary evidence. In the absence of contrary material or precedent from the Revenue, deletion of that addition was upheld and the Revenue's appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4939