Charitable trust registration requires a specified-violation notice; settled cash deposits and related-party payments did not justify cancellation or ...
External development charges trigger TDS under section 194C, while disputed administrative payments require factual verification and fresh adjudicatio...
Section 270AA penalty immunity requires identified statutory defaults and a hearing before rejection; reassessment disclosure may constitute under-rep...
Section 80JJAA employee-cost deduction allowed for deployed staff but barred against transfer-pricing income enhancement, with pricing issues remanded...
Transfer-pricing methodology protects commercially genuine associated-enterprise payments, while pre-2016 secondary adjustments and related notional i...
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expa...
Cross-examination rights in Customs Broker revocation inquiries require witness examination; procedural denial may be cured through fresh adjudication...
Page of 4891
Press 'Enter' after typing page number.
1381 to 1400 of 97820 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
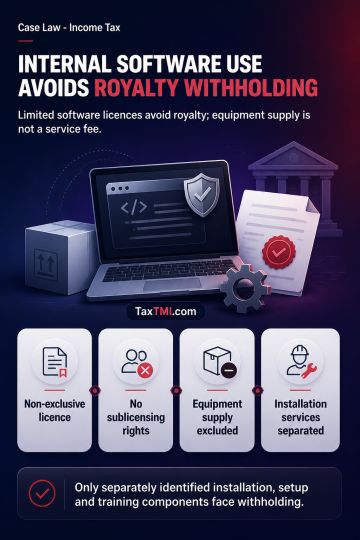
Payments for a non-exclusive, non-transferable and non-sublicensable licence to use software internally do not constitute royalty under Article 12(3) of the India-USA DTAA where the licensor retains copyright and proprietary rights and the user cannot commercially exploit, modify, sublicense, reverse engineer or copy the software except for backup. Such payments concern use of a copyrighted article, eliminating withholding-tax liability as royalty. Payments for video-conferencing equipment and allied products are not fees for technical services merely because installation, setup and training accompany the supply. Withholding applies only to the separately identified installation, setup and training component, subject to the applicable India-Germany DTAA rate.
Payments for a non-exclusive, non-transferable and non-sublicensable licence to use software internally do not constitute royalty under Article 12(3) of the India-USA DTAA where the licensor retains copyright and proprietary rights and the user cannot commercially exploit, modify, sublicense, reverse engineer or copy the software except for backup. Such payments concern use of a copyrighted article, eliminating withholding-tax liability as royalty. Payments for video-conferencing equipment and allied products are not fees for technical services merely because installation, setup and training accompany the supply. Withholding applies only to the separately identified installation, setup and training component, subject to the applicable India-Germany DTAA rate.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891