Service of notice and contractual debt acknowledgment preserved insolvency admission against a corporate guarantor despite limitation and natural just...
Original works exemption excludes standalone boulder transportation, leaving subcontracted railway-project transport services subject to service tax l...
Annual production capacity determinations excluding stenter galleries support refunds for unconstitutional excise levies without an unjust-enrichment ...
Vicarious liability for cheque dishonour requires specific allegations of responsibility and cheque signatory; generic director allegations cannot sus...
IT Resilience Index requires market infrastructure institutions to automate resilience scoring, early warnings, and continuous service-delivery monito...
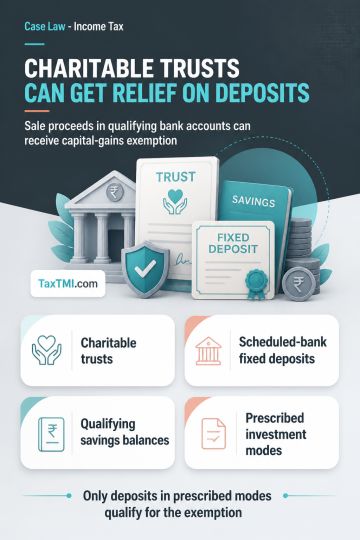
For charitable trusts, fixed deposits and balances in a scheduled-bank savings account created from capital-asset sale proceeds constitute acquisition of another capital asset for capital-gains exemption under section 11(1A). A bank deposit is a permissible investment mode, and its status as a capital asset does not depend on the deposit duration. Eligibility requires sale proceeds to be invested only in prescribed modes; qualifying fixed deposits and savings balances therefore fall within the exemption.
For charitable trusts, fixed deposits and balances in a scheduled-bank savings account created from capital-asset sale proceeds constitute acquisition of another capital asset for capital-gains exemption under section 11(1A). A bank deposit is a permissible investment mode, and its status as a capital asset does not depend on the deposit duration. Eligibility requires sale proceeds to be invested only in prescribed modes; qualifying fixed deposits and savings balances therefore fall within the exemption.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888