Agricultural land classification requires cumulative factual indicators, while industrial-purpose land and absent agricultural use defeat reinvestment...
Composite residential flat exemption upheld where supplementary agreement merged adjoining units and additional evidence supported the taxpayer's inve...
Urgent interim relief exception permits commercial suit without pre-institution mediation where immediate disclosure and asset protection are genuinel...
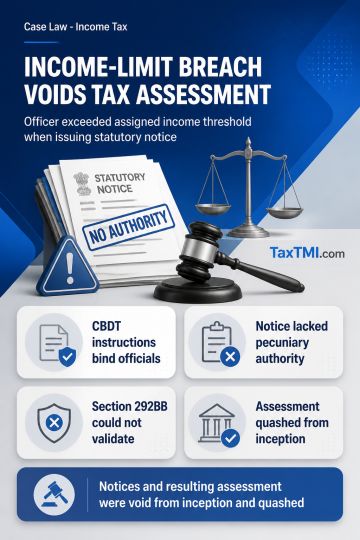
Pecuniary jurisdiction over statutory notices under section 143(2) must comply with CBDT instructions allocating cases by returned-income limits. Where an Income-tax Officer issues the notice despite the returned income exceeding that officer's prescribed limit, the defect concerns pecuniary rather than territorial jurisdiction; the territorial-jurisdiction objection rule does not apply. CBDT instructions bind the Department, and issue of a jurisdictional notice by an officer without pecuniary authority is an illegality, not a procedural irregularity capable of validation under section 292BB. The notices and consequential assessment were therefore treated as void from inception and quashed; other grounds remained academic.
Pecuniary jurisdiction over statutory notices under section 143(2) must comply with CBDT instructions allocating cases by returned-income limits. Where an Income-tax Officer issues the notice despite the returned income exceeding that officer's prescribed limit, the defect concerns pecuniary rather than territorial jurisdiction; the territorial-jurisdiction objection rule does not apply. CBDT instructions bind the Department, and issue of a jurisdictional notice by an officer without pecuniary authority is an illegality, not a procedural irregularity capable of validation under section 292BB. The notices and consequential assessment were therefore treated as void from inception and quashed; other grounds remained academic.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891