Transfer pricing comparability prioritises reliable external CUPs and foreign-currency LIBOR benchmarks for exports, borrowings and delayed receivable...
Section 153C satisfaction and seized electronic records sustained unexplained-investment addition, subject to proportionate ownership-share verificati...
Natural justice in insolvency-professional discipline requires disclosed material; notices based on extraneous material and ignored defences are vitia...
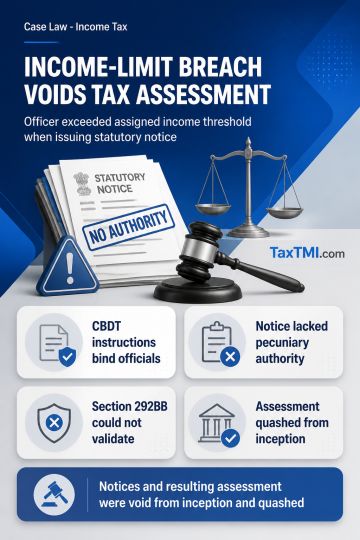
Pecuniary jurisdiction over statutory notices under section 143(2) must comply with CBDT instructions allocating cases by returned-income limits. Where an Income-tax Officer issues the notice despite the returned income exceeding that officer's prescribed limit, the defect concerns pecuniary rather than territorial jurisdiction; the territorial-jurisdiction objection rule does not apply. CBDT instructions bind the Department, and issue of a jurisdictional notice by an officer without pecuniary authority is an illegality, not a procedural irregularity capable of validation under section 292BB. The notices and consequential assessment were therefore treated as void from inception and quashed; other grounds remained academic.
Pecuniary jurisdiction over statutory notices under section 143(2) must comply with CBDT instructions allocating cases by returned-income limits. Where an Income-tax Officer issues the notice despite the returned income exceeding that officer's prescribed limit, the defect concerns pecuniary rather than territorial jurisdiction; the territorial-jurisdiction objection rule does not apply. CBDT instructions bind the Department, and issue of a jurisdictional notice by an officer without pecuniary authority is an illegality, not a procedural irregularity capable of validation under section 292BB. The notices and consequential assessment were therefore treated as void from inception and quashed; other grounds remained academic.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891