Service of notice and contractual debt acknowledgment preserved insolvency admission against a corporate guarantor despite limitation and natural just...
Original works exemption excludes standalone boulder transportation, leaving subcontracted railway-project transport services subject to service tax l...
Annual production capacity determinations excluding stenter galleries support refunds for unconstitutional excise levies without an unjust-enrichment ...
Vicarious liability for cheque dishonour requires specific allegations of responsibility and cheque signatory; generic director allegations cannot sus...
IT Resilience Index requires market infrastructure institutions to automate resilience scoring, early warnings, and continuous service-delivery monito...
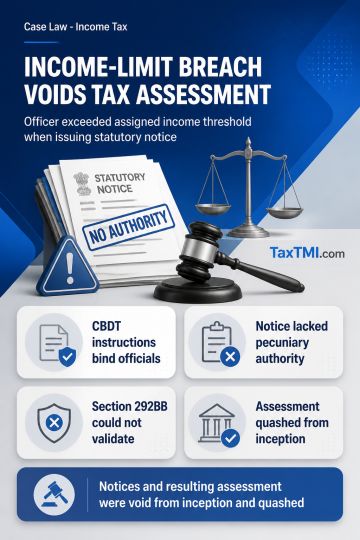
Pecuniary jurisdiction over statutory notices under section 143(2) must comply with CBDT instructions allocating cases by returned-income limits. Where an Income-tax Officer issues the notice despite the returned income exceeding that officer's prescribed limit, the defect concerns pecuniary rather than territorial jurisdiction; the territorial-jurisdiction objection rule does not apply. CBDT instructions bind the Department, and issue of a jurisdictional notice by an officer without pecuniary authority is an illegality, not a procedural irregularity capable of validation under section 292BB. The notices and consequential assessment were therefore treated as void from inception and quashed; other grounds remained academic.
Pecuniary jurisdiction over statutory notices under section 143(2) must comply with CBDT instructions allocating cases by returned-income limits. Where an Income-tax Officer issues the notice despite the returned income exceeding that officer's prescribed limit, the defect concerns pecuniary rather than territorial jurisdiction; the territorial-jurisdiction objection rule does not apply. CBDT instructions bind the Department, and issue of a jurisdictional notice by an officer without pecuniary authority is an illegality, not a procedural irregularity capable of validation under section 292BB. The notices and consequential assessment were therefore treated as void from inception and quashed; other grounds remained academic.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888