Natural justice in insolvency-professional discipline requires disclosed material; notices based on extraneous material and ignored defences are vitia...
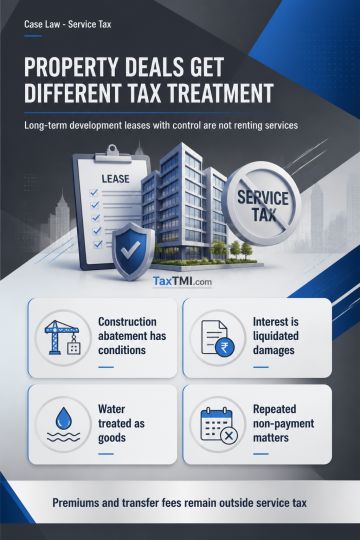
Development rights transfers treated as immovable property, while construction abatement applies and repeated non-payment permits extended service-tax...
Page of 4888
Press 'Enter' after typing page number.
1521 to 1540 of 97750 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
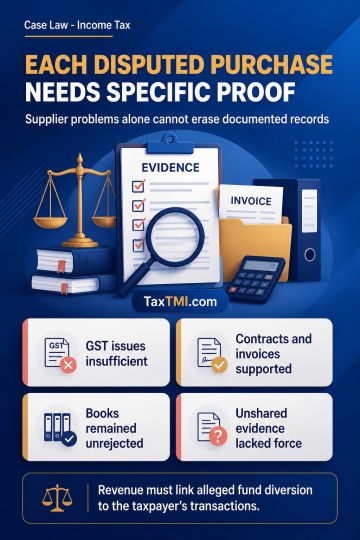
GST deregistration, subsequent non-filing of returns, a supplier's absence from its address, or vehicle discrepancies do not alone establish that documented purchases are bogus. Purchase orders, subcontract agreements, invoices, delivery records, e-way bills, GST records, attendance and project records, and banking payments support the genuineness of materials, labour, housekeeping and manpower transactions, particularly where books remain unrejected and contracts are undisputed. Incomplete third-party statements or chat extracts not supplied to the taxpayer, and not linked to its transactions, lack evidentiary force. Revenue must establish a nexus between alleged supplier fund diversion and taxpayer transactions; a taxpayer denying a transaction cannot be required to prove a negative.
GST deregistration, subsequent non-filing of returns, a supplier's absence from its address, or vehicle discrepancies do not alone establish that documented purchases are bogus. Purchase orders, subcontract agreements, invoices, delivery records, e-way bills, GST records, attendance and project records, and banking payments support the genuineness of materials, labour, housekeeping and manpower transactions, particularly where books remain unrejected and contracts are undisputed. Incomplete third-party statements or chat extracts not supplied to the taxpayer, and not linked to its transactions, lack evidentiary force. Revenue must establish a nexus between alleged supplier fund diversion and taxpayer transactions; a taxpayer denying a transaction cannot be required to prove a negative.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888