Service of notice and contractual debt acknowledgment preserved insolvency admission against a corporate guarantor despite limitation and natural just...
Original works exemption excludes standalone boulder transportation, leaving subcontracted railway-project transport services subject to service tax l...
Annual production capacity determinations excluding stenter galleries support refunds for unconstitutional excise levies without an unjust-enrichment ...
Vicarious liability for cheque dishonour requires specific allegations of responsibility and cheque signatory; generic director allegations cannot sus...
IT Resilience Index requires market infrastructure institutions to automate resilience scoring, early warnings, and continuous service-delivery monito...
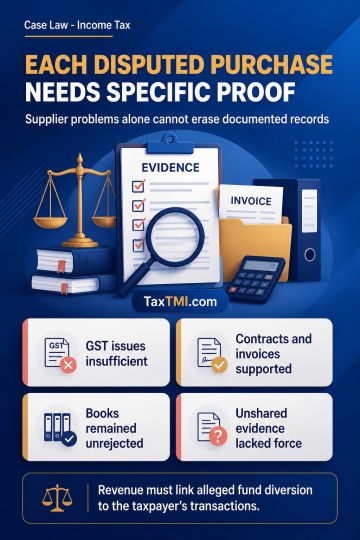
GST deregistration, subsequent non-filing of returns, a supplier's absence from its address, or vehicle discrepancies do not alone establish that documented purchases are bogus. Purchase orders, subcontract agreements, invoices, delivery records, e-way bills, GST records, attendance and project records, and banking payments support the genuineness of materials, labour, housekeeping and manpower transactions, particularly where books remain unrejected and contracts are undisputed. Incomplete third-party statements or chat extracts not supplied to the taxpayer, and not linked to its transactions, lack evidentiary force. Revenue must establish a nexus between alleged supplier fund diversion and taxpayer transactions; a taxpayer denying a transaction cannot be required to prove a negative.
GST deregistration, subsequent non-filing of returns, a supplier's absence from its address, or vehicle discrepancies do not alone establish that documented purchases are bogus. Purchase orders, subcontract agreements, invoices, delivery records, e-way bills, GST records, attendance and project records, and banking payments support the genuineness of materials, labour, housekeeping and manpower transactions, particularly where books remain unrejected and contracts are undisputed. Incomplete third-party statements or chat extracts not supplied to the taxpayer, and not linked to its transactions, lack evidentiary force. Revenue must establish a nexus between alleged supplier fund diversion and taxpayer transactions; a taxpayer denying a transaction cannot be required to prove a negative.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888