Reassessment disclosure requirements permit stated reasons without revealing information sources, but prior-taxation claims require full examination b...
Independent assessment discretion and corroborated electronic evidence determine validity of on-money additions and undisclosed-consideration assessme...
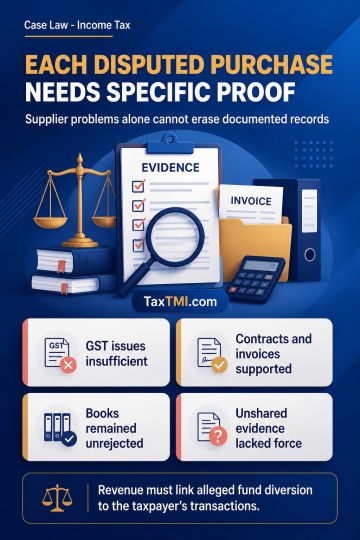
GST deregistration, subsequent non-filing of returns, a supplier's absence from its address, or vehicle discrepancies do not alone establish that documented purchases are bogus. Purchase orders, subcontract agreements, invoices, delivery records, e-way bills, GST records, attendance and project records, and banking payments support the genuineness of materials, labour, housekeeping and manpower transactions, particularly where books remain unrejected and contracts are undisputed. Incomplete third-party statements or chat extracts not supplied to the taxpayer, and not linked to its transactions, lack evidentiary force. Revenue must establish a nexus between alleged supplier fund diversion and taxpayer transactions; a taxpayer denying a transaction cannot be required to prove a negative.
GST deregistration, subsequent non-filing of returns, a supplier's absence from its address, or vehicle discrepancies do not alone establish that documented purchases are bogus. Purchase orders, subcontract agreements, invoices, delivery records, e-way bills, GST records, attendance and project records, and banking payments support the genuineness of materials, labour, housekeeping and manpower transactions, particularly where books remain unrejected and contracts are undisputed. Incomplete third-party statements or chat extracts not supplied to the taxpayer, and not linked to its transactions, lack evidentiary force. Revenue must establish a nexus between alleged supplier fund diversion and taxpayer transactions; a taxpayer denying a transaction cannot be required to prove a negative.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888