Alternative statutory remedy and unexplained delay barred writ review of customs confiscation adjudication, leaving merits for appellate consideration...
Authorised courier due diligence protects against penalties where declared exports conceal prohibited goods despite proper documentation and customs p...
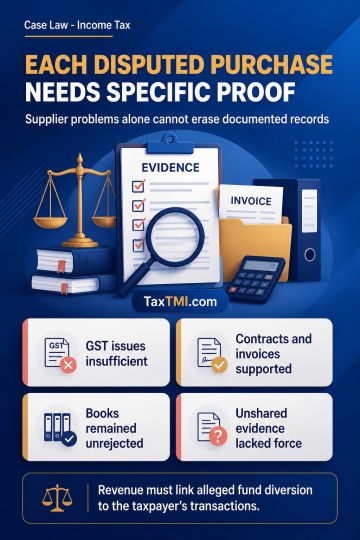
GST deregistration, subsequent non-filing of returns, a supplier's absence from its address, or vehicle discrepancies do not alone establish that documented purchases are bogus. Purchase orders, subcontract agreements, invoices, delivery records, e-way bills, GST records, attendance and project records, and banking payments support the genuineness of materials, labour, housekeeping and manpower transactions, particularly where books remain unrejected and contracts are undisputed. Incomplete third-party statements or chat extracts not supplied to the taxpayer, and not linked to its transactions, lack evidentiary force. Revenue must establish a nexus between alleged supplier fund diversion and taxpayer transactions; a taxpayer denying a transaction cannot be required to prove a negative.
GST deregistration, subsequent non-filing of returns, a supplier's absence from its address, or vehicle discrepancies do not alone establish that documented purchases are bogus. Purchase orders, subcontract agreements, invoices, delivery records, e-way bills, GST records, attendance and project records, and banking payments support the genuineness of materials, labour, housekeeping and manpower transactions, particularly where books remain unrejected and contracts are undisputed. Incomplete third-party statements or chat extracts not supplied to the taxpayer, and not linked to its transactions, lack evidentiary force. Revenue must establish a nexus between alleged supplier fund diversion and taxpayer transactions; a taxpayer denying a transaction cannot be required to prove a negative.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894