Composite residential flat exemption upheld where supplementary agreement merged adjoining units and additional evidence supported the taxpayer's inve...
Urgent interim relief exception permits commercial suit without pre-institution mediation where immediate disclosure and asset protection are genuinel...
Portal order discrepancies invalidated rectification rejection, requiring fresh reasoned consideration after hearing and prompt communication of the o...
Page of 4888
Press 'Enter' after typing page number.
1601 to 1620 of 97755 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
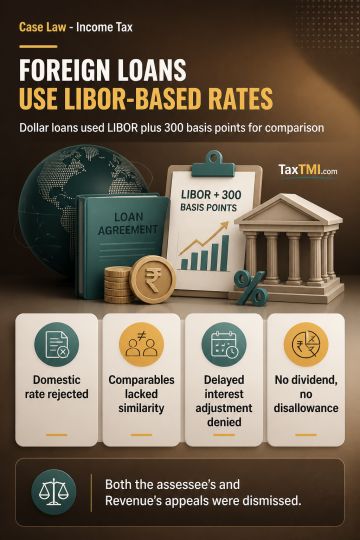
Foreign-currency loans repayable in US dollars were benchmarked using LIBOR plus 300 basis points rather than a domestic lending rate, and that transfer-pricing direction was sustained. Under TNMM, comparables must satisfy functional and product comparability; sectorally distinct engineering services and aluminium-capacitor manufacturing entities were excluded. No arm's-length interest adjustment applied to delayed associated-enterprise receivables where no interest was charged to either associated or non-associated enterprises and transaction pricing already reflected margins. Expenditure relating to investments could not be disallowed where no exempt dividend income was received or receivable during the year. The assessee's and Revenue's appeals were dismissed.
Foreign-currency loans repayable in US dollars were benchmarked using LIBOR plus 300 basis points rather than a domestic lending rate, and that transfer-pricing direction was sustained. Under TNMM, comparables must satisfy functional and product comparability; sectorally distinct engineering services and aluminium-capacitor manufacturing entities were excluded. No arm's-length interest adjustment applied to delayed associated-enterprise receivables where no interest was charged to either associated or non-associated enterprises and transaction pricing already reflected margins. Expenditure relating to investments could not be disallowed where no exempt dividend income was received or receivable during the year. The assessee's and Revenue's appeals were dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888