Concessional corporate tax option under section 115BAA survives procedural documentary lapses when statutory compliance and earlier exercise are estab...
Penny-stock additions require transaction-specific evidence; general investigation material alone cannot establish undisclosed income or accommodation...
Transfer pricing comparability prioritises reliable external CUPs and foreign-currency LIBOR benchmarks for exports, borrowings and delayed receivable...
Section 153C satisfaction and seized electronic records sustained unexplained-investment addition, subject to proportionate ownership-share verificati...
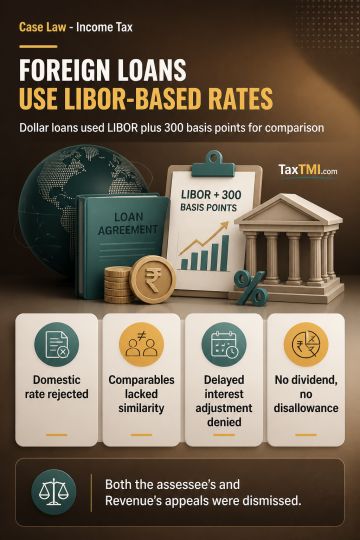
Foreign-currency loans repayable in US dollars were benchmarked using LIBOR plus 300 basis points rather than a domestic lending rate, and that transfer-pricing direction was sustained. Under TNMM, comparables must satisfy functional and product comparability; sectorally distinct engineering services and aluminium-capacitor manufacturing entities were excluded. No arm's-length interest adjustment applied to delayed associated-enterprise receivables where no interest was charged to either associated or non-associated enterprises and transaction pricing already reflected margins. Expenditure relating to investments could not be disallowed where no exempt dividend income was received or receivable during the year. The assessee's and Revenue's appeals were dismissed.
Foreign-currency loans repayable in US dollars were benchmarked using LIBOR plus 300 basis points rather than a domestic lending rate, and that transfer-pricing direction was sustained. Under TNMM, comparables must satisfy functional and product comparability; sectorally distinct engineering services and aluminium-capacitor manufacturing entities were excluded. No arm's-length interest adjustment applied to delayed associated-enterprise receivables where no interest was charged to either associated or non-associated enterprises and transaction pricing already reflected margins. Expenditure relating to investments could not be disallowed where no exempt dividend income was received or receivable during the year. The assessee's and Revenue's appeals were dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888