Service of notice and contractual debt acknowledgment preserved insolvency admission against a corporate guarantor despite limitation and natural just...
Original works exemption excludes standalone boulder transportation, leaving subcontracted railway-project transport services subject to service tax l...
Annual production capacity determinations excluding stenter galleries support refunds for unconstitutional excise levies without an unjust-enrichment ...
Vicarious liability for cheque dishonour requires specific allegations of responsibility and cheque signatory; generic director allegations cannot sus...
IT Resilience Index requires market infrastructure institutions to automate resilience scoring, early warnings, and continuous service-delivery monito...
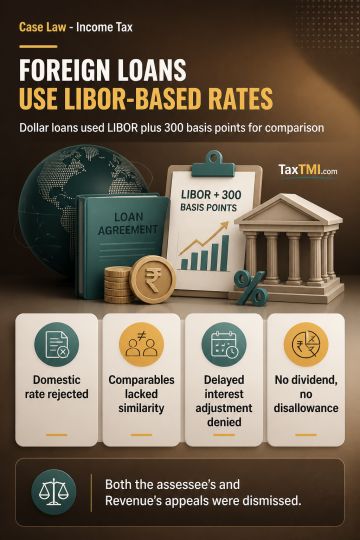
Foreign-currency loans repayable in US dollars were benchmarked using LIBOR plus 300 basis points rather than a domestic lending rate, and that transfer-pricing direction was sustained. Under TNMM, comparables must satisfy functional and product comparability; sectorally distinct engineering services and aluminium-capacitor manufacturing entities were excluded. No arm's-length interest adjustment applied to delayed associated-enterprise receivables where no interest was charged to either associated or non-associated enterprises and transaction pricing already reflected margins. Expenditure relating to investments could not be disallowed where no exempt dividend income was received or receivable during the year. The assessee's and Revenue's appeals were dismissed.
Foreign-currency loans repayable in US dollars were benchmarked using LIBOR plus 300 basis points rather than a domestic lending rate, and that transfer-pricing direction was sustained. Under TNMM, comparables must satisfy functional and product comparability; sectorally distinct engineering services and aluminium-capacitor manufacturing entities were excluded. No arm's-length interest adjustment applied to delayed associated-enterprise receivables where no interest was charged to either associated or non-associated enterprises and transaction pricing already reflected margins. Expenditure relating to investments could not be disallowed where no exempt dividend income was received or receivable during the year. The assessee's and Revenue's appeals were dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888