Agricultural land classification requires cumulative factual indicators, while industrial-purpose land and absent agricultural use defeat reinvestment...
Composite residential flat exemption upheld where supplementary agreement merged adjoining units and additional evidence supported the taxpayer's inve...
Urgent interim relief exception permits commercial suit without pre-institution mediation where immediate disclosure and asset protection are genuinel...
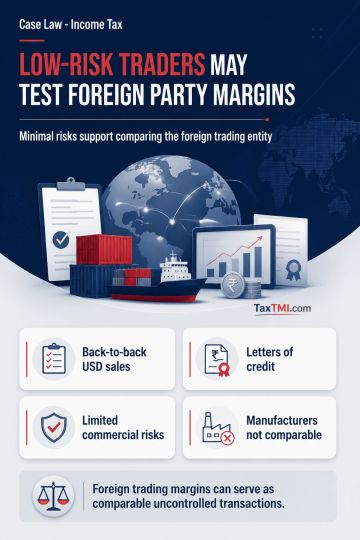
High-sea merchant trading conducted through back-to-back USD sales, supported by letters of credit, may justify selecting the foreign associated enterprise as the tested party under the Resale Price Method where the Indian entity bears no significant inventory, collection, market or foreign-exchange risk and has minimal working-capital needs. The associated enterprise's trading margins with unrelated parties can serve as comparable uncontrolled transactions. Steel manufacturers are not functionally comparable to pure merchant traders because their functions, assets and risks materially differ. Currency conversion does not materially affect the analysis where both purchase and sale transactions are denominated in USD.
High-sea merchant trading conducted through back-to-back USD sales, supported by letters of credit, may justify selecting the foreign associated enterprise as the tested party under the Resale Price Method where the Indian entity bears no significant inventory, collection, market or foreign-exchange risk and has minimal working-capital needs. The associated enterprise's trading margins with unrelated parties can serve as comparable uncontrolled transactions. Steel manufacturers are not functionally comparable to pure merchant traders because their functions, assets and risks materially differ. Currency conversion does not materially affect the analysis where both purchase and sale transactions are denominated in USD.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891