Withdrawal of obsolete FEMA circulars streamlines rules on external commercial borrowings, non-resident bond investments, and money transfer sub-agent...
Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Page of 4937
Press 'Enter' after typing page number.
2001 to 2020 of 98735 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
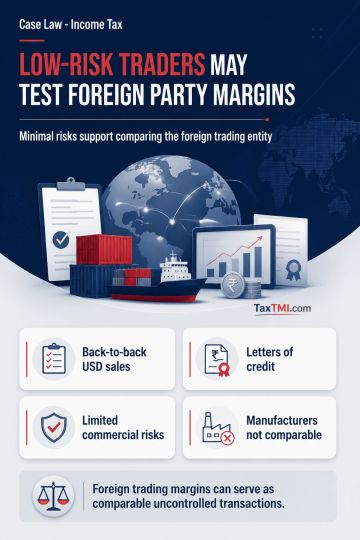
High-sea merchant trading conducted through back-to-back USD sales, supported by letters of credit, may justify selecting the foreign associated enterprise as the tested party under the Resale Price Method where the Indian entity bears no significant inventory, collection, market or foreign-exchange risk and has minimal working-capital needs. The associated enterprise's trading margins with unrelated parties can serve as comparable uncontrolled transactions. Steel manufacturers are not functionally comparable to pure merchant traders because their functions, assets and risks materially differ. Currency conversion does not materially affect the analysis where both purchase and sale transactions are denominated in USD.
High-sea merchant trading conducted through back-to-back USD sales, supported by letters of credit, may justify selecting the foreign associated enterprise as the tested party under the Resale Price Method where the Indian entity bears no significant inventory, collection, market or foreign-exchange risk and has minimal working-capital needs. The associated enterprise's trading margins with unrelated parties can serve as comparable uncontrolled transactions. Steel manufacturers are not functionally comparable to pure merchant traders because their functions, assets and risks materially differ. Currency conversion does not materially affect the analysis where both purchase and sale transactions are denominated in USD.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937