Service of notice and contractual debt acknowledgment preserved insolvency admission against a corporate guarantor despite limitation and natural just...
Original works exemption excludes standalone boulder transportation, leaving subcontracted railway-project transport services subject to service tax l...
Annual production capacity determinations excluding stenter galleries support refunds for unconstitutional excise levies without an unjust-enrichment ...
Vicarious liability for cheque dishonour requires specific allegations of responsibility and cheque signatory; generic director allegations cannot sus...
IT Resilience Index requires market infrastructure institutions to automate resilience scoring, early warnings, and continuous service-delivery monito...
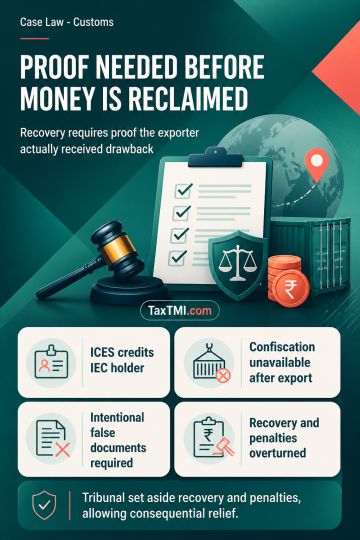
Drawback recovery from an exporter whose goods were shipped under another entity's IEC requires evidence that the exporter actually received the drawback; ICES ordinarily credits the IEC holder's bank account. Recovery is an execution proceeding, but interest liability arises only upon proof of payment to that exporter. Goods already taken outside India are exported goods, not export goods liable to confiscation under section 113, so consequential section 114 penalties fail. Export through another person's IEC may breach foreign trade law, but section 114AA penalties require evidence of knowing or intentional use of materially false customs declarations or documents. The Tribunal set aside recovery and penalties, allowing the appeals with consequential relief.
Drawback recovery from an exporter whose goods were shipped under another entity's IEC requires evidence that the exporter actually received the drawback; ICES ordinarily credits the IEC holder's bank account. Recovery is an execution proceeding, but interest liability arises only upon proof of payment to that exporter. Goods already taken outside India are exported goods, not export goods liable to confiscation under section 113, so consequential section 114 penalties fail. Export through another person's IEC may breach foreign trade law, but section 114AA penalties require evidence of knowing or intentional use of materially false customs declarations or documents. The Tribunal set aside recovery and penalties, allowing the appeals with consequential relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888