Concessional corporate tax option under section 115BAA survives procedural documentary lapses when statutory compliance and earlier exercise are estab...
Page of 4937
Press 'Enter' after typing page number.
2481 to 2500 of 98738 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
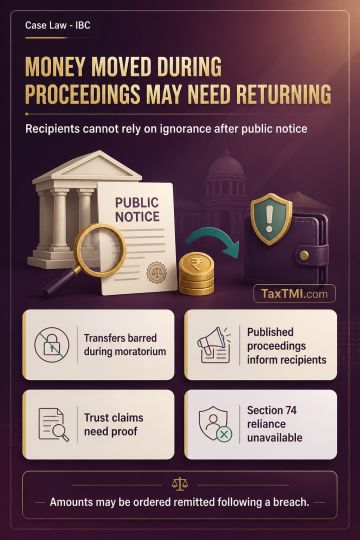
Transfers of a corporate debtor's funds during the CIRP moratorium are prohibited where made without the Resolution Professional's knowledge, and transferred amounts may be directed to be remitted. Public announcement and publication of CIRP proceedings create deemed knowledge of the moratorium, preventing a recipient from relying on ignorance as a defence. A claim that transferred funds were held in trust requires proof of a trust relationship and a basis for identifying the funds as trust money; an unsupported assertion is insufficient. Proceedings for a moratorium breach may be pursued under Section 60(5) read with Section 14(1)(b). Reliance on Section 74 was unavailable where it was not previously pleaded and had been omitted by the 2026 amendment.
Transfers of a corporate debtor's funds during the CIRP moratorium are prohibited where made without the Resolution Professional's knowledge, and transferred amounts may be directed to be remitted. Public announcement and publication of CIRP proceedings create deemed knowledge of the moratorium, preventing a recipient from relying on ignorance as a defence. A claim that transferred funds were held in trust requires proof of a trust relationship and a basis for identifying the funds as trust money; an unsupported assertion is insufficient. Proceedings for a moratorium breach may be pursued under Section 60(5) read with Section 14(1)(b). Reliance on Section 74 was unavailable where it was not previously pleaded and had been omitted by the 2026 amendment.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937