Transfer-pricing comparability requires exclusion of financially illogical super-profit comparables and correction of unsupported annual-report and ma...
Charitable character assessment preserves Section 80G approval despite inclusive spiritual teachings and incidental religious expenditure within the s...
Penalty proceedings for cash-loan acceptance require assessment proceedings and recorded Assessing Officer satisfaction; absent these, the proceedings...
Functional comparability governs software-service benchmarking: dissimilar companies are excluded, while related-party filters, margins and working-ca...
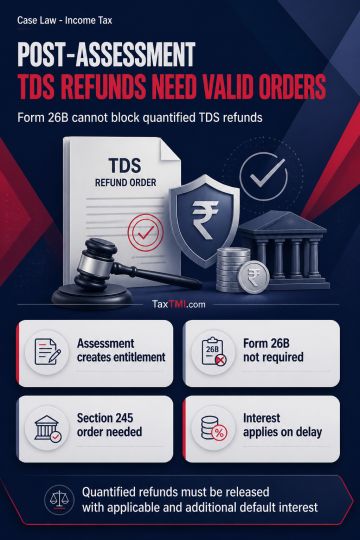
TDS refunds quantified under an assessment or appellate order under Section 201 constitute a crystallised entitlement carrying statutory interest. Form 26B, which concerns processing and adjustment of TDS statements under Section 200A and Rule 31A, cannot be required for such post-assessment refunds. Outstanding demands may justify withholding or adjustment only through a legally valid order under Section 245; demands linked to the assessee's PAN or sister TANs do not otherwise permit withholding. The quantified refunds were directed to be released with applicable interest, with additional interest for default.
TDS refunds quantified under an assessment or appellate order under Section 201 constitute a crystallised entitlement carrying statutory interest. Form 26B, which concerns processing and adjustment of TDS statements under Section 200A and Rule 31A, cannot be required for such post-assessment refunds. Outstanding demands may justify withholding or adjustment only through a legally valid order under Section 245; demands linked to the assessee's PAN or sister TANs do not otherwise permit withholding. The quantified refunds were directed to be released with applicable interest, with additional interest for default.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891