Split consignment classification treated complementary motorcycle parts as one imported motorcycle, sustaining valuation, confiscation and importer li...
Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
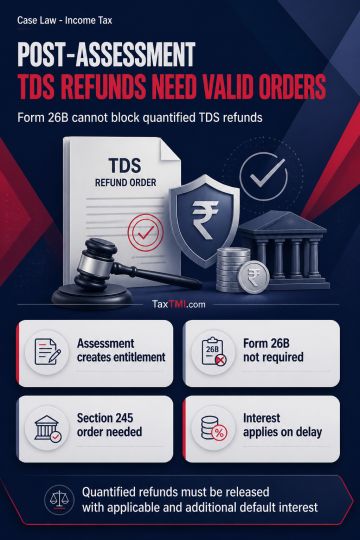
TDS refunds quantified under an assessment or appellate order under Section 201 constitute a crystallised entitlement carrying statutory interest. Form 26B, which concerns processing and adjustment of TDS statements under Section 200A and Rule 31A, cannot be required for such post-assessment refunds. Outstanding demands may justify withholding or adjustment only through a legally valid order under Section 245; demands linked to the assessee's PAN or sister TANs do not otherwise permit withholding. The quantified refunds were directed to be released with applicable interest, with additional interest for default.
TDS refunds quantified under an assessment or appellate order under Section 201 constitute a crystallised entitlement carrying statutory interest. Form 26B, which concerns processing and adjustment of TDS statements under Section 200A and Rule 31A, cannot be required for such post-assessment refunds. Outstanding demands may justify withholding or adjustment only through a legally valid order under Section 245; demands linked to the assessee's PAN or sister TANs do not otherwise permit withholding. The quantified refunds were directed to be released with applicable interest, with additional interest for default.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894