Handicraft job work receives concessional GST only for registered principals and predominantly handmade goods; commercial resin articles remain taxabl...
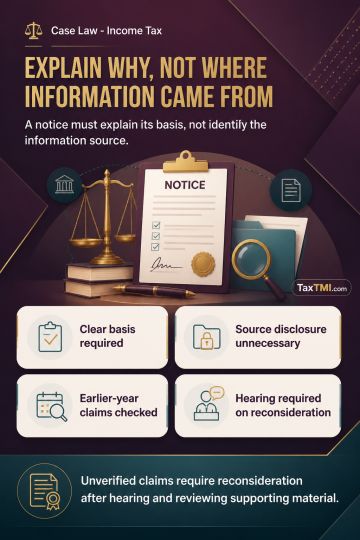
Reassessment disclosure requirements permit stated reasons without revealing information sources, but prior-taxation claims require full examination b...
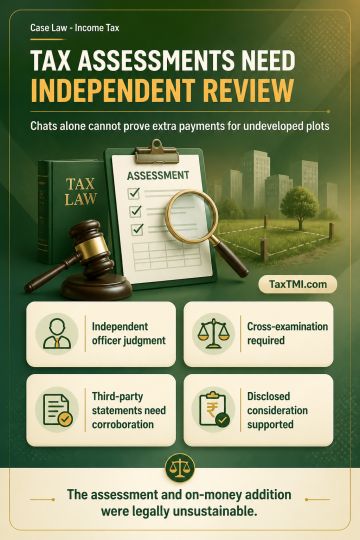
Independent assessment discretion and corroborated electronic evidence determine validity of on-money additions and undisclosed-consideration assessme...
Interest on delayed refunds arising from appellate-effect orders for Assessment Years 2014-15 to 2016-17 was directed to be computed under Section 244A(1A) from 1 December 2025 until payment, with additional Section 244A interest for September 2026 if payment was not made within the stipulated period. The Assessing Officer was required to secure consequential payment through the CPC. For Assessment Year 2014-15, the Assessing Officer was also required to verify the difference between tax deducted at source credit in the appellate-effect order and Form 26AS; if a short grant was established, interest under Section 244A(1) would run from 1 April 2014 until payment. No further direction applied to Assessment Year 2009-10.
Interest on delayed refunds arising from appellate-effect orders for Assessment Years 2014-15 to 2016-17 was directed to be computed under Section 244A(1A) from 1 December 2025 until payment, with additional Section 244A interest for September 2026 if payment was not made within the stipulated period. The Assessing Officer was required to secure consequential payment through the CPC. For Assessment Year 2014-15, the Assessing Officer was also required to verify the difference between tax deducted at source credit in the appellate-effect order and Form 26AS; if a short grant was established, interest under Section 244A(1) would run from 1 April 2014 until payment. No further direction applied to Assessment Year 2009-10.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4939