Concessional corporate tax option under section 115BAA survives procedural documentary lapses when statutory compliance and earlier exercise are estab...
Penny-stock additions require transaction-specific evidence; general investigation material alone cannot establish undisclosed income or accommodation...
Transfer pricing comparability prioritises reliable external CUPs and foreign-currency LIBOR benchmarks for exports, borrowings and delayed receivable...
Section 153C satisfaction and seized electronic records sustained unexplained-investment addition, subject to proportionate ownership-share verificati...
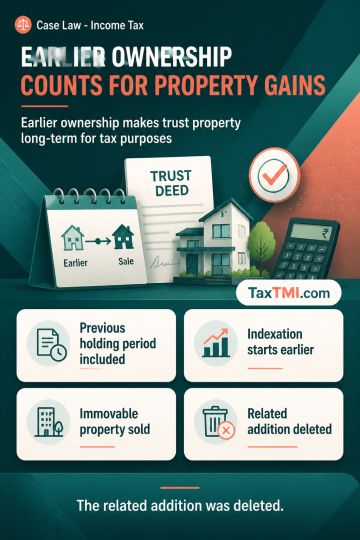
For property devolving on a beneficiary upon dissolution of a private family trust, the previous owner's holding period must be included where the previous owner's cost is adopted under section 49(1). Explanation 1(b) to section 2(42A) requires that deemed holding period to determine whether the asset is long-term; the properties therefore qualify as long-term capital assets. The same holding period applies to indexed cost of acquisition, which must be computed from the year in which the previous owner first held the property. Gains on the sale of such devolved immovable properties are accordingly taxable as long-term capital gains, and the related addition was deleted.
For property devolving on a beneficiary upon dissolution of a private family trust, the previous owner's holding period must be included where the previous owner's cost is adopted under section 49(1). Explanation 1(b) to section 2(42A) requires that deemed holding period to determine whether the asset is long-term; the properties therefore qualify as long-term capital assets. The same holding period applies to indexed cost of acquisition, which must be computed from the year in which the previous owner first held the property. Gains on the sale of such devolved immovable properties are accordingly taxable as long-term capital gains, and the related addition was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897