Toy balloon tariff classification: functional heading prevails over residual rubber and festive article headings, supporting penalties for deliberate ...
Customs valuation using comparable contemporaneous imports can displace declared value, while missing speaking orders require pursuit before competent...
Foreign customs declarations and importer admissions established undervaluation, supporting sequential value redetermination, differential duty, and m...
Customs seizure safeguards prevent detention-based limitation avoidance and invalidate provisional release conditions for imported vehicles under an i...
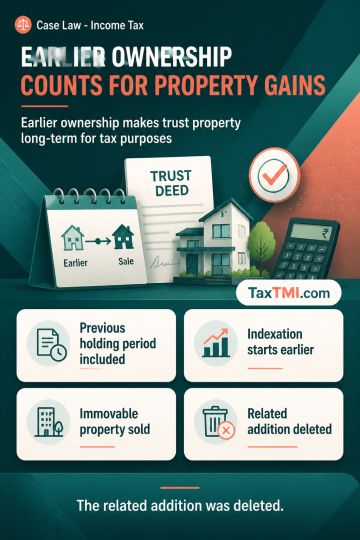
For property devolving on a beneficiary upon dissolution of a private family trust, the previous owner's holding period must be included where the previous owner's cost is adopted under section 49(1). Explanation 1(b) to section 2(42A) requires that deemed holding period to determine whether the asset is long-term; the properties therefore qualify as long-term capital assets. The same holding period applies to indexed cost of acquisition, which must be computed from the year in which the previous owner first held the property. Gains on the sale of such devolved immovable properties are accordingly taxable as long-term capital gains, and the related addition was deleted.
For property devolving on a beneficiary upon dissolution of a private family trust, the previous owner's holding period must be included where the previous owner's cost is adopted under section 49(1). Explanation 1(b) to section 2(42A) requires that deemed holding period to determine whether the asset is long-term; the properties therefore qualify as long-term capital assets. The same holding period applies to indexed cost of acquisition, which must be computed from the year in which the previous owner first held the property. Gains on the sale of such devolved immovable properties are accordingly taxable as long-term capital gains, and the related addition was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888