Belated Form 10B filing during Covid-19 cannot defeat charitable exemption where genuine hardship warrants condonation and substantial justice prevail...
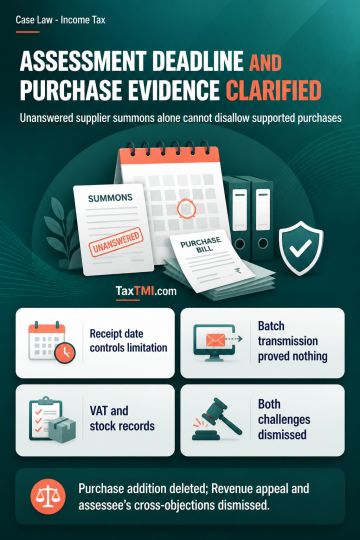
Limitation for consequential assessments runs from prescribed authority receipt, while verified purchases cannot be disallowed merely for unanswered s...
Page of 4894
Press 'Enter' after typing page number.
1821 to 1840 of 97867 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
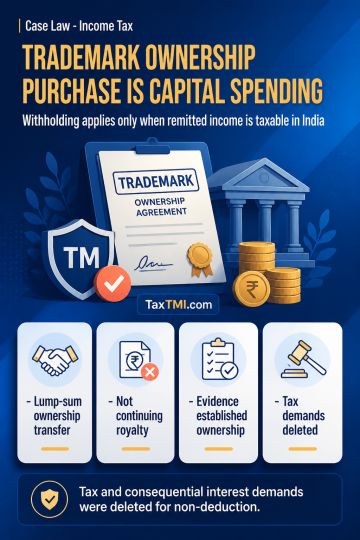
Outright acquisition of trademark ownership for lump-sum consideration constitutes acquisition of a capital asset rather than payment for the use of intellectual property or continuing royalty. A foreign remittance for such transfer does not by itself create a tax deduction obligation under section 195; withholding applies only where the remitted sum is chargeable to tax in India. Where the assignment agreement, transferred rights, valuation, commercial terms, ownership evidence and recipient's tax residency certificate establish an ownership transfer, the payer cannot be treated as in default for non-deduction of tax. Demands for tax and consequential interest under sections 201(1) and 201(1A) were deleted.
Outright acquisition of trademark ownership for lump-sum consideration constitutes acquisition of a capital asset rather than payment for the use of intellectual property or continuing royalty. A foreign remittance for such transfer does not by itself create a tax deduction obligation under section 195; withholding applies only where the remitted sum is chargeable to tax in India. Where the assignment agreement, transferred rights, valuation, commercial terms, ownership evidence and recipient's tax residency certificate establish an ownership transfer, the payer cannot be treated as in default for non-deduction of tax. Demands for tax and consequential interest under sections 201(1) and 201(1A) were deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894