Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Special insurance income computation preserves statutory deductions while limiting transfer-pricing, withholding and disallowance adjustments for gene...
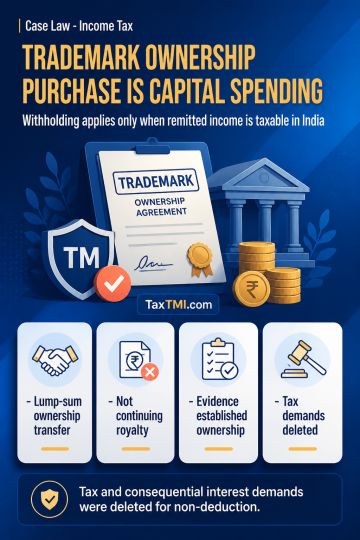
Outright acquisition of trademark ownership for lump-sum consideration constitutes acquisition of a capital asset rather than payment for the use of intellectual property or continuing royalty. A foreign remittance for such transfer does not by itself create a tax deduction obligation under section 195; withholding applies only where the remitted sum is chargeable to tax in India. Where the assignment agreement, transferred rights, valuation, commercial terms, ownership evidence and recipient's tax residency certificate establish an ownership transfer, the payer cannot be treated as in default for non-deduction of tax. Demands for tax and consequential interest under sections 201(1) and 201(1A) were deleted.
Outright acquisition of trademark ownership for lump-sum consideration constitutes acquisition of a capital asset rather than payment for the use of intellectual property or continuing royalty. A foreign remittance for such transfer does not by itself create a tax deduction obligation under section 195; withholding applies only where the remitted sum is chargeable to tax in India. Where the assignment agreement, transferred rights, valuation, commercial terms, ownership evidence and recipient's tax residency certificate establish an ownership transfer, the payer cannot be treated as in default for non-deduction of tax. Demands for tax and consequential interest under sections 201(1) and 201(1A) were deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4896