Penny-stock additions require transaction-specific evidence; general investigation material alone cannot establish undisclosed income or accommodation...
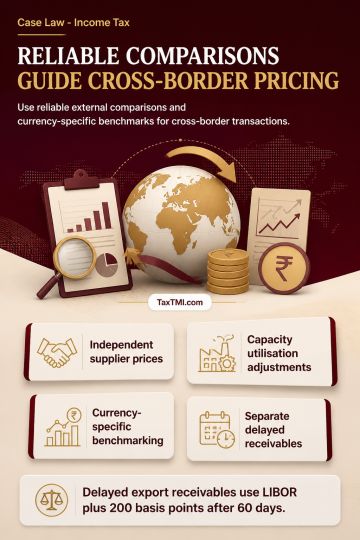
Transfer pricing comparability prioritises reliable external CUPs and foreign-currency LIBOR benchmarks for exports, borrowings and delayed receivable...
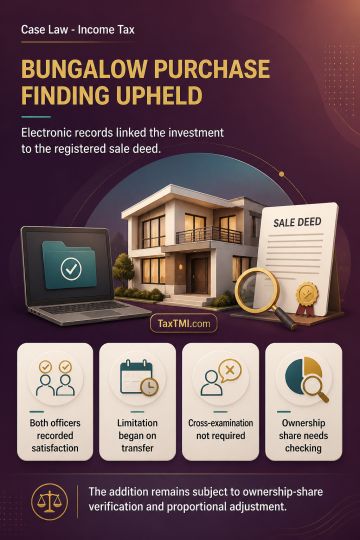
Section 153C satisfaction and seized electronic records sustained unexplained-investment addition, subject to proportionate ownership-share verificati...
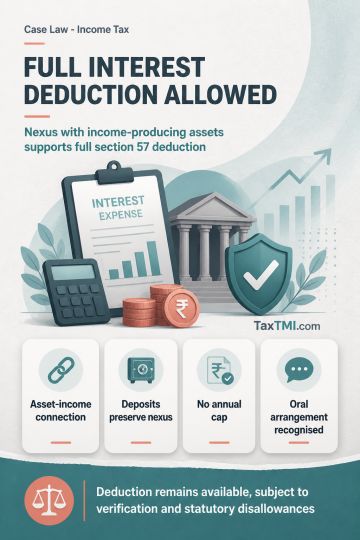
Interest expenditure under section 57 remains deductible where borrowings retain a real nexus with assets generating income taxable under Income from Other Sources. Conversion of investments into sale proceeds and then fixed or term deposits does not, by itself, break that nexus. Deduction is not limited to interest income realised in the same year; arithmetical equivalence between expenditure and annual income is not required. An oral interest arrangement may establish an existing liability when supported by conduct and historical treatment. The creditor's accounting method and timing of taxability of corresponding interest are independently determined and cannot restrict the borrower's otherwise allowable deduction, subject to year-wise quantification, verification, and separate statutory disallowances.
Interest expenditure under section 57 remains deductible where borrowings retain a real nexus with assets generating income taxable under Income from Other Sources. Conversion of investments into sale proceeds and then fixed or term deposits does not, by itself, break that nexus. Deduction is not limited to interest income realised in the same year; arithmetical equivalence between expenditure and annual income is not required. An oral interest arrangement may establish an existing liability when supported by conduct and historical treatment. The creditor's accounting method and timing of taxability of corresponding interest are independently determined and cannot restrict the borrower's otherwise allowable deduction, subject to year-wise quantification, verification, and separate statutory disallowances.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937