Educational approval requires mandatory State registration, but incidental surplus and trustee-owned land do not prove private benefit or profit motiv...
Judicial review of settlement orders cannot reopen settled customs notices, while statutory interest remains subject to verification and quantificatio...
Customs Broker licence lending for consideration justified revocation where exporter authorisation and client verification obligations were also breac...
Fraudulent import documents suspend limitation protection, while redemption of confiscated goods requires duty and interest despite bona fide purchase...
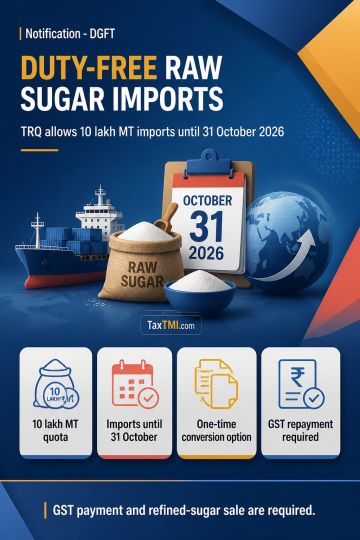
Raw sugar classified under Exim Code 170114 may be imported freely within a duty-free Tariff Rate Quota of 10 lakh MT up to 31 October 2026. Advance Authorisations issued under SION E52 receive a one-time option to convert to the TRQ Scheme for raw sugar actually imported before the notification date, including refined sugar produced or to be produced from that imported raw sugar. Conversion requires payment of GST exempted on import, domestic sale of the resulting refined sugar by 31 October 2026, and compliance with further prescribed conditions. DGFT will issue the administrative procedure for the TRQ and conversion process.
Raw sugar classified under Exim Code 170114 may be imported freely within a duty-free Tariff Rate Quota of 10 lakh MT up to 31 October 2026. Advance Authorisations issued under SION E52 receive a one-time option to convert to the TRQ Scheme for raw sugar actually imported before the notification date, including refined sugar produced or to be produced from that imported raw sugar. Conversion requires payment of GST exempted on import, domestic sale of the resulting refined sugar by 31 October 2026, and compliance with further prescribed conditions. DGFT will issue the administrative procedure for the TRQ and conversion process.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897