Related-party creditor exclusion bars CoC participation where lender rights show policy-making involvement, and post-CIRP assignment cannot cure ineli...
Rectification of apparent typographical errors may proceed without hearing when tax liability, input tax credit, and ruling substance remain unchanged...
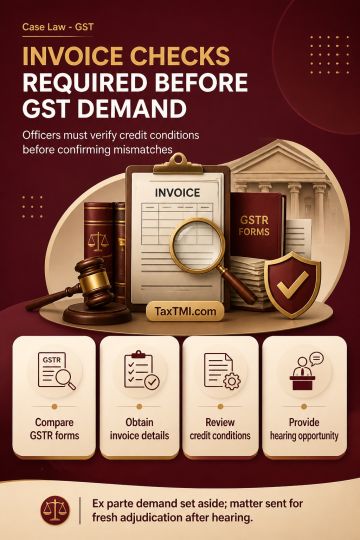
For input tax credit mismatches between FORM GSTR-3B and FORM GSTR-2A, the prescribed Circular requires the proper officer to obtain invoice details from the registered person and verify satisfaction of credit-availment conditions before confirming a demand. An ex parte demand was set aside because that verification had not occurred. Fresh consideration was directed on the taxpayer's representation, in compliance with the Circular and after a reasonable opportunity of hearing, without determination of the merits of the credit claim.
For input tax credit mismatches between FORM GSTR-3B and FORM GSTR-2A, the prescribed Circular requires the proper officer to obtain invoice details from the registered person and verify satisfaction of credit-availment conditions before confirming a demand. An ex parte demand was set aside because that verification had not occurred. Fresh consideration was directed on the taxpayer's representation, in compliance with the Circular and after a reasonable opportunity of hearing, without determination of the merits of the credit claim.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937