Service of notice and contractual debt acknowledgment preserved insolvency admission against a corporate guarantor despite limitation and natural just...
Original works exemption excludes standalone boulder transportation, leaving subcontracted railway-project transport services subject to service tax l...
Annual production capacity determinations excluding stenter galleries support refunds for unconstitutional excise levies without an unjust-enrichment ...
Vicarious liability for cheque dishonour requires specific allegations of responsibility and cheque signatory; generic director allegations cannot sus...
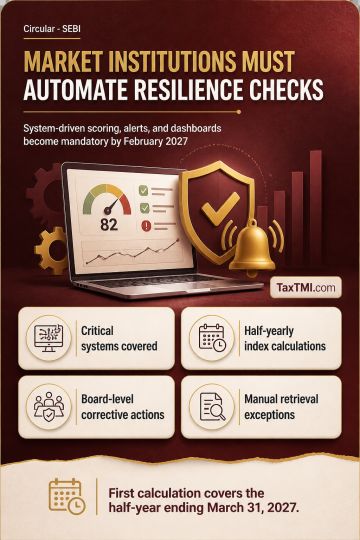
IT Resilience Index requires market infrastructure institutions to automate resilience scoring, early warnings, and continuous service-delivery monito...
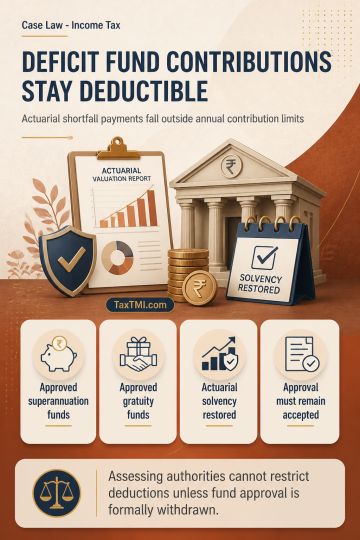
Actuarial deficit contributions made to an approved superannuation fund to align fund assets with actuarial liabilities are distinguished from ordinary annual or initial contributions. Because their purpose is to remedy an actuarial shortfall, they are not subject to the Rule 87 ceiling on annual contributions, preserving the fund's solvency. Similarly, contributions bridging actuarial liability and available assets in an approved gratuity fund are not ordinary annual contributions subject to the Rule 103 ceiling. Unless approval is formally withdrawn, the assessing authority must accept the fund's approved status and cannot, during assessment, question compliance with the Rules to restrict the deduction.
Actuarial deficit contributions made to an approved superannuation fund to align fund assets with actuarial liabilities are distinguished from ordinary annual or initial contributions. Because their purpose is to remedy an actuarial shortfall, they are not subject to the Rule 87 ceiling on annual contributions, preserving the fund's solvency. Similarly, contributions bridging actuarial liability and available assets in an approved gratuity fund are not ordinary annual contributions subject to the Rule 103 ceiling. Unless approval is formally withdrawn, the assessing authority must accept the fund's approved status and cannot, during assessment, question compliance with the Rules to restrict the deduction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4907