Split consignment classification treated complementary motorcycle parts as one imported motorcycle, sustaining valuation, confiscation and importer li...
Page of 4897
Press 'Enter' after typing page number.
81 to 100 of 97923 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
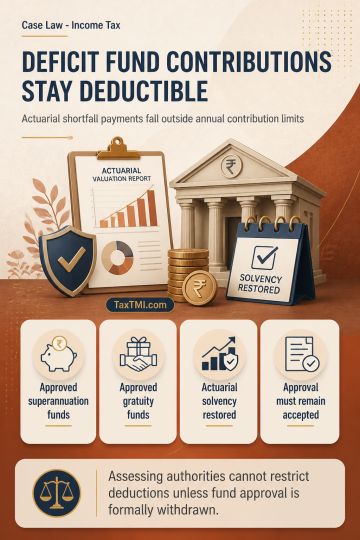
Actuarial deficit contributions made to an approved superannuation fund to align fund assets with actuarial liabilities are distinguished from ordinary annual or initial contributions. Because their purpose is to remedy an actuarial shortfall, they are not subject to the Rule 87 ceiling on annual contributions, preserving the fund's solvency. Similarly, contributions bridging actuarial liability and available assets in an approved gratuity fund are not ordinary annual contributions subject to the Rule 103 ceiling. Unless approval is formally withdrawn, the assessing authority must accept the fund's approved status and cannot, during assessment, question compliance with the Rules to restrict the deduction.
Actuarial deficit contributions made to an approved superannuation fund to align fund assets with actuarial liabilities are distinguished from ordinary annual or initial contributions. Because their purpose is to remedy an actuarial shortfall, they are not subject to the Rule 87 ceiling on annual contributions, preserving the fund's solvency. Similarly, contributions bridging actuarial liability and available assets in an approved gratuity fund are not ordinary annual contributions subject to the Rule 103 ceiling. Unless approval is formally withdrawn, the assessing authority must accept the fund's approved status and cannot, during assessment, question compliance with the Rules to restrict the deduction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897