Governmental authority status supports construction-service exemption, while pre-cutoff contract and stamp-duty compliance requires verification on re...
Automated Free Sale and Commerce Certificates enable paperless processing while retaining risk-based manual verification for selected exporter applica...
Employee stock-shortage penalties do not constitute consideration for services, preventing GST collection under Schedule II in employment relationship...
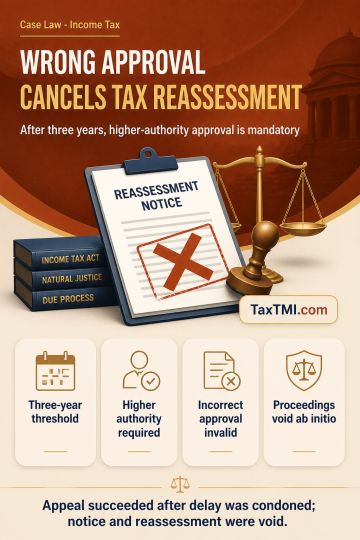
For reassessment notices issued more than three years after the end of the relevant assessment year, prior approval from the higher specified authority under section 151(ii) is a jurisdictional precondition. Approval from the Principal Commissioner under section 151(i) is insufficient where section 151(ii) applies. Applying this requirement to assessment year 2018-19, the section 148 notice and reassessment under sections 147 and 144B were void ab initio because the required approval was not obtained. The appeal was allowed after condoning delay, and the reassessment was quashed.
For reassessment notices issued more than three years after the end of the relevant assessment year, prior approval from the higher specified authority under section 151(ii) is a jurisdictional precondition. Approval from the Principal Commissioner under section 151(i) is insufficient where section 151(ii) applies. Applying this requirement to assessment year 2018-19, the section 148 notice and reassessment under sections 147 and 144B were void ab initio because the required approval was not obtained. The appeal was allowed after condoning delay, and the reassessment was quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929