Transfer-pricing treatment of ITeS margins excludes pass-through tax recoveries and separate delayed-receivables interest after working-capital adjust...
Capacity-utilisation adjustments under TNMM can neutralise substantiated COVID-related idle costs where underutilisation materially affects profitabil...
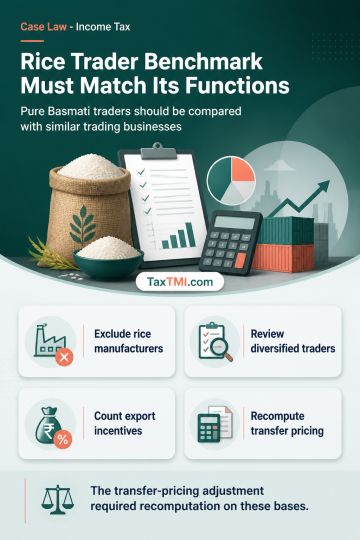
TNMM functional comparability requires excluding rice manufacturers from a pure Basmati rice trader's benchmark and recognising operating export recei...
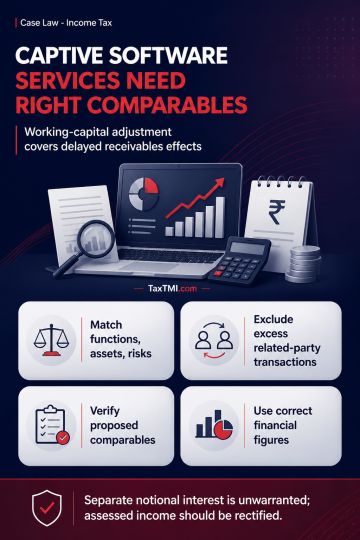
Working-capital adjustment subsumes delayed-receivable effects in TNMM benchmarking of captive software-development services, avoiding separate notion...
Page of 4929
Press 'Enter' after typing page number.
2181 to 2200 of 98580 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
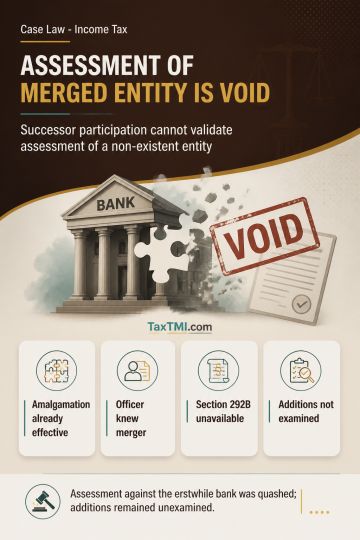
Assessment issued in the name of an amalgamated entity that has ceased to exist is an incurable jurisdictional defect and void from inception. Where the Assessing Officer knew of the amalgamation, the successor entity's participation cannot validate the assessment or cure it as a procedural irregularity under section 292B. Supreme Court precedent treats such assessment as a substantive illegality affecting jurisdiction. Consequently, the assessment against the erstwhile bank was quashed, and the merits of the additions were not examined.
Assessment issued in the name of an amalgamated entity that has ceased to exist is an incurable jurisdictional defect and void from inception. Where the Assessing Officer knew of the amalgamation, the successor entity's participation cannot validate the assessment or cure it as a procedural irregularity under section 292B. Supreme Court precedent treats such assessment as a substantive illegality affecting jurisdiction. Consequently, the assessment against the erstwhile bank was quashed, and the merits of the additions were not examined.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929