Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
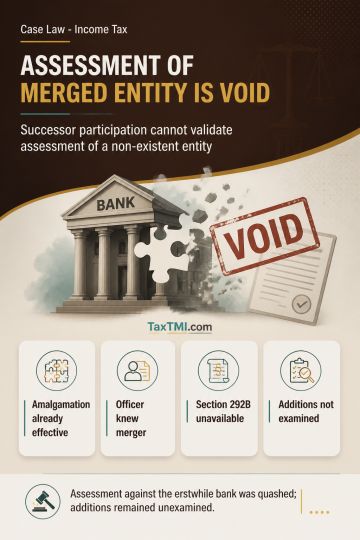
Assessment issued in the name of an amalgamated entity that has ceased to exist is an incurable jurisdictional defect and void from inception. Where the Assessing Officer knew of the amalgamation, the successor entity's participation cannot validate the assessment or cure it as a procedural irregularity under section 292B. Supreme Court precedent treats such assessment as a substantive illegality affecting jurisdiction. Consequently, the assessment against the erstwhile bank was quashed, and the merits of the additions were not examined.
Assessment issued in the name of an amalgamated entity that has ceased to exist is an incurable jurisdictional defect and void from inception. Where the Assessing Officer knew of the amalgamation, the successor entity's participation cannot validate the assessment or cure it as a procedural irregularity under section 292B. Supreme Court precedent treats such assessment as a substantive illegality affecting jurisdiction. Consequently, the assessment against the erstwhile bank was quashed, and the merits of the additions were not examined.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937