ODR arbitration participation remains mandatory after failed conciliation, while jurisdictional and maintainability objections stay available before t...
Transparency in technical bid evaluation requires disclosed standards and recorded reasons; opaque scoring invalidated tender awards and required fres...
Automated export obligation extensions remove separate regional applications after committee approval for Advance Authorisation and EPCG authorisation...
International cargo transhipment through Indian ports continues with Customs-controlled storage, re-export safeguards, and coordinated multi-station m...
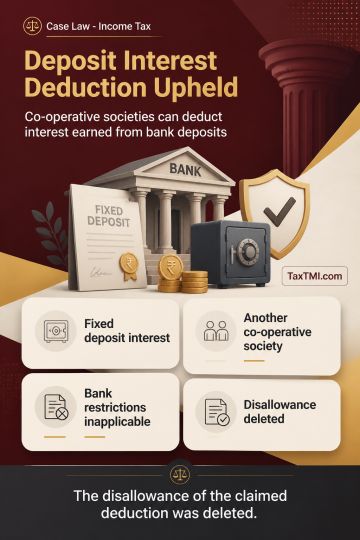
Interest earned by a co-operative housing society on fixed deposits with co-operative banks qualifies for deduction under section 80P(2)(d), provided the investment is with another co-operative society. A co-operative bank registered under applicable co-operative societies law remains a co-operative society for that purpose. Section 80P(4) restricts deductions claimed by co-operative banks themselves and does not limit the deduction available to an investing co-operative society. This interpretation is consistent with the liberal construction of beneficial provisions and Tribunal decisions applying the principle. The disallowance of the claimed deduction was deleted.
Interest earned by a co-operative housing society on fixed deposits with co-operative banks qualifies for deduction under section 80P(2)(d), provided the investment is with another co-operative society. A co-operative bank registered under applicable co-operative societies law remains a co-operative society for that purpose. Section 80P(4) restricts deductions claimed by co-operative banks themselves and does not limit the deduction available to an investing co-operative society. This interpretation is consistent with the liberal construction of beneficial provisions and Tribunal decisions applying the principle. The disallowance of the claimed deduction was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897