Split consignment classification treated complementary motorcycle parts as one imported motorcycle, sustaining valuation, confiscation and importer li...
Page of 4897
Press 'Enter' after typing page number.
81 to 100 of 97923 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
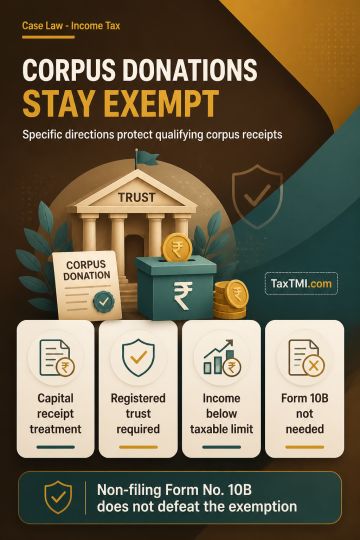
Corpus donations received by a charitable trust with a specific direction to form part of its corpus are treated as exempt capital receipts. A harmonious reading of the provisions on voluntary contributions, charitable-trust exemptions and the relevant CBDT circular supports exclusion of such receipts from taxable income. Where the trust is registered under the applicable charitable registration provisions and its income, excluding exempt corpus receipts, remains below the taxable limit, the audit requirement and filing of Form No. 10B are not attracted. Non-furnishing of Form No. 10B therefore does not defeat the exemption for qualifying corpus contributions.
Corpus donations received by a charitable trust with a specific direction to form part of its corpus are treated as exempt capital receipts. A harmonious reading of the provisions on voluntary contributions, charitable-trust exemptions and the relevant CBDT circular supports exclusion of such receipts from taxable income. Where the trust is registered under the applicable charitable registration provisions and its income, excluding exempt corpus receipts, remains below the taxable limit, the audit requirement and filing of Form No. 10B are not attracted. Non-furnishing of Form No. 10B therefore does not defeat the exemption for qualifying corpus contributions.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897