Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Special insurance income computation preserves statutory deductions while limiting transfer-pricing, withholding and disallowance adjustments for gene...
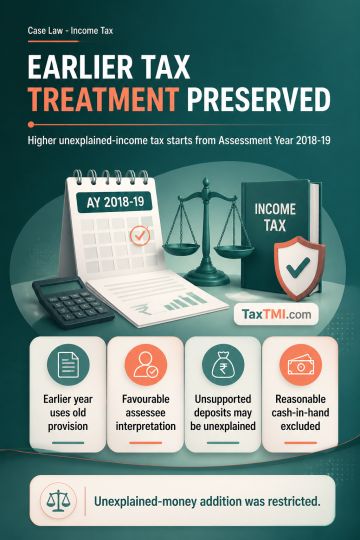
Enhanced taxation of unexplained income under the amended Section 115BBE was treated as prospective, applying from Assessment Year 2018-19 rather than Assessment Year 2017-18. Where High Court decisions conflict and no binding jurisdictional High Court or Supreme Court ruling exists, the interpretation favourable to the assessee applies; tax for the earlier year is therefore computed under the unamended provision. Cash deposits used to repay a bank loan may be treated as unexplained money under Section 69A when their source lacks documentary support, but the entire deposit need not be added if reasonable cash-in-hand is available for ordinary requirements. The unexplained-money addition was consequently restricted.
Enhanced taxation of unexplained income under the amended Section 115BBE was treated as prospective, applying from Assessment Year 2018-19 rather than Assessment Year 2017-18. Where High Court decisions conflict and no binding jurisdictional High Court or Supreme Court ruling exists, the interpretation favourable to the assessee applies; tax for the earlier year is therefore computed under the unamended provision. Cash deposits used to repay a bank loan may be treated as unexplained money under Section 69A when their source lacks documentary support, but the entire deposit need not be added if reasonable cash-in-hand is available for ordinary requirements. The unexplained-money addition was consequently restricted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897