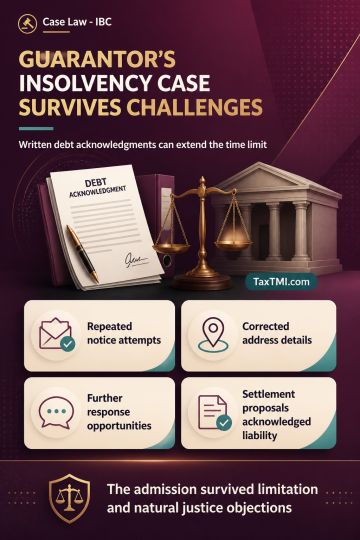
Service of notice and contractual debt acknowledgment preserved insolvency admission against a corporate guarantor despite limitation and natural just...
Original works exemption excludes standalone boulder transportation, leaving subcontracted railway-project transport services subject to service tax l...
Annual production capacity determinations excluding stenter galleries support refunds for unconstitutional excise levies without an unjust-enrichment ...
Vicarious liability for cheque dishonour requires specific allegations of responsibility and cheque signatory; generic director allegations cannot sus...
IT Resilience Index requires market infrastructure institutions to automate resilience scoring, early warnings, and continuous service-delivery monito...
Judicial review of Settlement Commission orders is limited to...
Judicial review of settlement orders cannot reopen settled customs notices, while statutory interest remains subject to verification and quantification.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Judicial review of Settlement Commission orders is limited to jurisdictional or statutory infirmity, prejudice, fraud, bias or malice and cannot operate as an appellate reassessment of the underlying adjudication. Where parties voluntarily settle proceedings arising from a show cause notice without pursuing the statutory appeal, they cannot reopen the notice's validity on limitation or reasonable-period grounds by challenging a consequential interest direction. Statutory interest remains a consequence of customs duty liability despite settlement of the duty quantum. Verification and quantification of further interest by the jurisdictional Commissioner may therefore be directed, subject to any independently maintainable challenge to the statutory computation.
Judicial review of Settlement Commission orders is limited to jurisdictional or statutory infirmity, prejudice, fraud, bias or malice and cannot operate as an appellate reassessment of the underlying adjudication. Where parties voluntarily settle proceedings arising from a show cause notice without pursuing the statutory appeal, they cannot reopen the notice's validity on limitation or reasonable-period grounds by challenging a consequential interest direction. Statutory interest remains a consequence of customs duty liability despite settlement of the duty quantum. Verification and quantification of further interest by the jurisdictional Commissioner may therefore be directed, subject to any independently maintainable challenge to the statutory computation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910