Charitable trust registration requires a specified-violation notice; settled cash deposits and related-party payments did not justify cancellation or ...
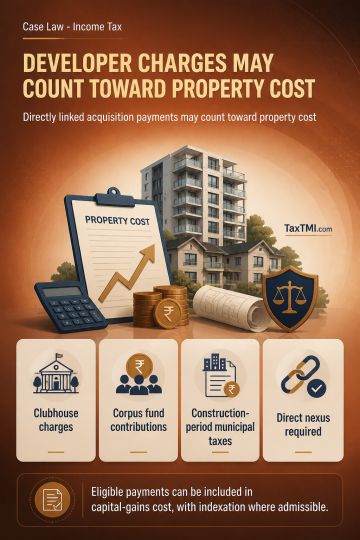
External development charges trigger TDS under section 194C, while disputed administrative payments require factual verification and fresh adjudicatio...
Section 270AA penalty immunity requires identified statutory defaults and a hearing before rejection; reassessment disclosure may constitute under-rep...
Section 80JJAA employee-cost deduction allowed for deployed staff but barred against transfer-pricing income enhancement, with pricing issues remanded...
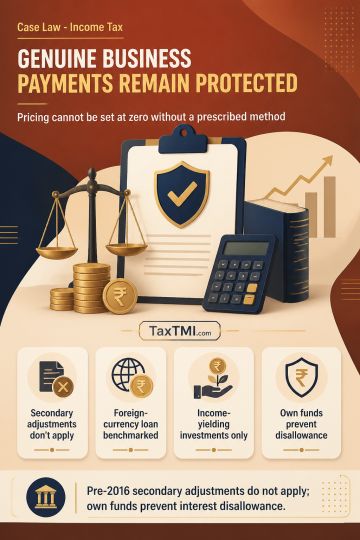
Transfer-pricing methodology protects commercially genuine associated-enterprise payments, while pre-2016 secondary adjustments and related notional i...
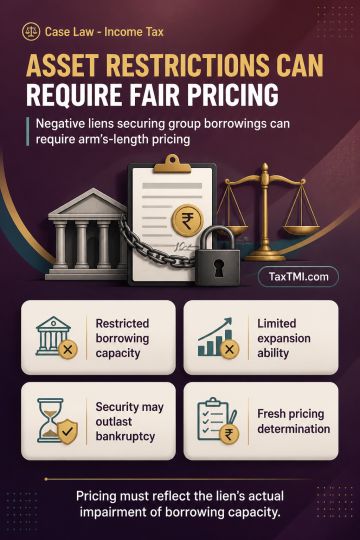
Negative liens over operating assets can constitute international transactions requiring arm's-length pricing reflecting restricted borrowing and expa...
Cross-examination rights in Customs Broker revocation inquiries require witness examination; procedural denial may be cured through fresh adjudication...
Judicial review of Settlement Commission orders is limited to...
Judicial review of settlement orders cannot reopen settled customs notices, while statutory interest remains subject to verification and quantification.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Judicial review of Settlement Commission orders is limited to jurisdictional or statutory infirmity, prejudice, fraud, bias or malice and cannot operate as an appellate reassessment of the underlying adjudication. Where parties voluntarily settle proceedings arising from a show cause notice without pursuing the statutory appeal, they cannot reopen the notice's validity on limitation or reasonable-period grounds by challenging a consequential interest direction. Statutory interest remains a consequence of customs duty liability despite settlement of the duty quantum. Verification and quantification of further interest by the jurisdictional Commissioner may therefore be directed, subject to any independently maintainable challenge to the statutory computation.
Judicial review of Settlement Commission orders is limited to jurisdictional or statutory infirmity, prejudice, fraud, bias or malice and cannot operate as an appellate reassessment of the underlying adjudication. Where parties voluntarily settle proceedings arising from a show cause notice without pursuing the statutory appeal, they cannot reopen the notice's validity on limitation or reasonable-period grounds by challenging a consequential interest direction. Statutory interest remains a consequence of customs duty liability despite settlement of the duty quantum. Verification and quantification of further interest by the jurisdictional Commissioner may therefore be directed, subject to any independently maintainable challenge to the statutory computation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912