Reassessment sanction under extended limitation required approval from the competent specified authority, invalidating proceedings approved by an inco...
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
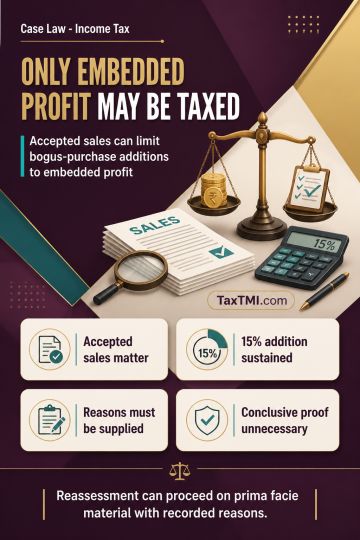
Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
Page of 4915
Press 'Enter' after typing page number.
1661 to 1680 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Judicial review of Settlement Commission orders is limited to...
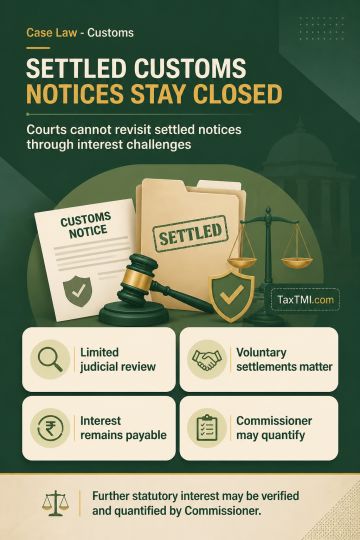
Judicial review of settlement orders cannot reopen settled customs notices, while statutory interest remains subject to verification and quantification.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Judicial review of Settlement Commission orders is limited to jurisdictional or statutory infirmity, prejudice, fraud, bias or malice and cannot operate as an appellate reassessment of the underlying adjudication. Where parties voluntarily settle proceedings arising from a show cause notice without pursuing the statutory appeal, they cannot reopen the notice's validity on limitation or reasonable-period grounds by challenging a consequential interest direction. Statutory interest remains a consequence of customs duty liability despite settlement of the duty quantum. Verification and quantification of further interest by the jurisdictional Commissioner may therefore be directed, subject to any independently maintainable challenge to the statutory computation.
Judicial review of Settlement Commission orders is limited to jurisdictional or statutory infirmity, prejudice, fraud, bias or malice and cannot operate as an appellate reassessment of the underlying adjudication. Where parties voluntarily settle proceedings arising from a show cause notice without pursuing the statutory appeal, they cannot reopen the notice's validity on limitation or reasonable-period grounds by challenging a consequential interest direction. Statutory interest remains a consequence of customs duty liability despite settlement of the duty quantum. Verification and quantification of further interest by the jurisdictional Commissioner may therefore be directed, subject to any independently maintainable challenge to the statutory computation.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915